
Dividing a House in an Avalon, CA Catalina Divorce
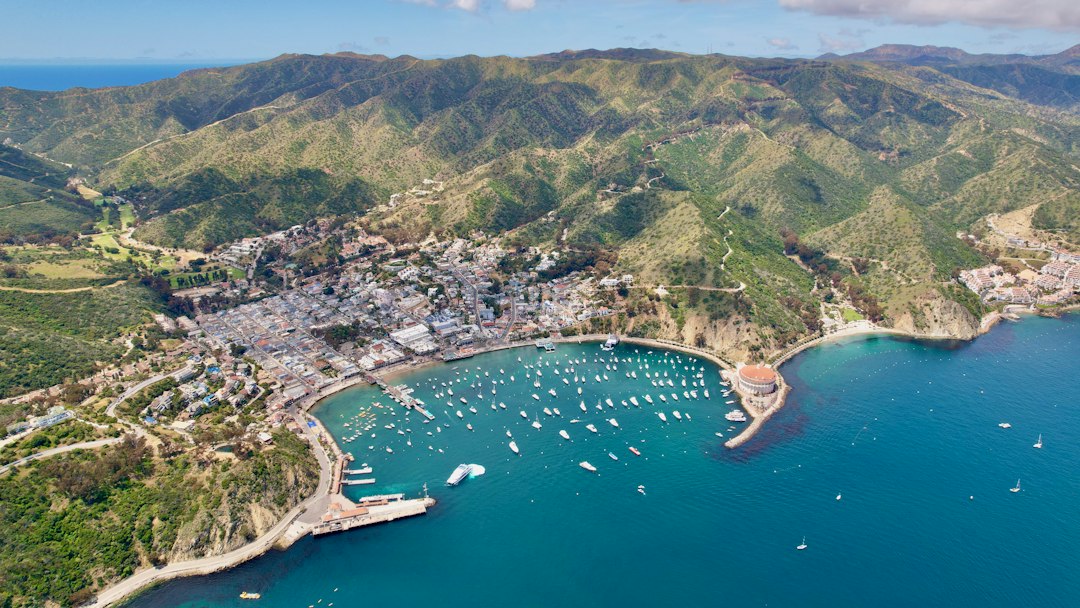
California divides community property equally in a divorce. But “equally” gets complicated fast when the asset is a house on an island with roughly 3,460 year-round residents. There are also almost no comparable sales to appraise against. Avalon is the only incorporated city on Santa Catalina Island.
You can reach it only by ferry, helicopter, or small aircraft. Its housing market behaves nothing like the mainland cities where this same law applies. If you’re dividing a home here, our Avalon divorce page covers the local sale process. This piece covers the community property rules driving the decision in the first place.
California Is a Community Property State — What That Means Here
Family Code §760 defines community property broadly. It covers all property, real or personal, that a married person acquires during the marriage while domiciled in California. It doesn’t matter whose name is on the title.
A house bought during the marriage with community funds is community property even if only one spouse’s name appears on the deed. Family Code §2550 then requires the court to divide the community estate equally between the spouses upon dissolution.
The exception is when the parties agree in writing (or stipulate in open court) to something different. For a single asset like a house, “equally” usually means one of three outcomes:
- sell it and split the proceeds
- have one spouse buy out the other’s interest
- or — less commonly — continue to co-own it under a post-divorce agreement
The general rules on who keeps the house and how the split is calculated apply the same way in Avalon as anywhere else in California. We’ve laid out the baseline mechanics in our guide to who gets the house in a California divorce. What’s different in Avalon is almost everything downstream of that baseline rule.
Why an Island Housing Market Complicates an Equal Division
Equal division depends on knowing what the house is worth. That’s harder to pin down here than almost anywhere else in the county, since the city has roughly one square mile of developed land.
Avalon’s housing stock is small, and much of it dates to the early 20th century. Many sales involve vacation or investment buyers, not the owner-occupant comparables an appraiser would use on the mainland.
Inventory is thin enough that in a given month there may be only a handful of recent closed sales to draw from. The city also draws roughly a million visitors a year. Because of that tourism-driven economy, some housing that looks comparable is really short-term rental or commercial-adjacent property.
That property doesn’t appraise the same way. Divorcing couples here often need a certified appraiser with specific Catalina Island experience. A general Los Angeles County appraiser pulling from mainland comps isn’t enough.
Even then, the appraisal is more of an informed estimate than the tight range a dense suburban market would produce.
Short-Term Rental Licenses Add a Wrinkle Most Appraisers Miss
A meaningful share of Avalon housing stock operates as a vacation rental. The city regulates that use tightly enough that it can directly affect what a divorcing couple’s house is actually worth. Under the city’s transient rental ordinance, renting for stays under 30 days requires a Transient Rental License.
The city caps the combined total of Transient Rental Licenses, Conditional Use Permits, and grandfathered Conditional Use Permits at 410 units citywide. Once that cap is reached, new applicants go onto a waitlist or lottery rather than simply applying and receiving one.
A License is generally non-transferable, except in a single one-time transfer to immediate family. An existing Conditional Use Permit is automatically lost upon the property’s second sale. If the house being divided already carries one of these licenses or permits, that income-producing status is a real asset.
But it may not survive a sale to a third party the way either spouse assumes. That depends on how many times the property has already changed hands and how the eventual transfer is set up. Confirm this with the city before an appraisal or settlement locks in a value. That value may assume rental income the next owner can’t actually collect.
Buyout, Sale, or Co-Ownership: The Three Paths
A buyout is the cleanest path when both spouses want it. In a buyout, one spouse keeps the house and pays the other half of the net equity. This is often done by refinancing or trading other community assets of equal value.
It only works if that spouse can actually qualify to refinance a Catalina Island property, and not every mainland lender is set up to do that. A straight sale and split of proceeds is usually the simplest path when neither spouse wants to keep the house.
It also helps when thin island inventory leaves the appraised value uncertain. In that case, an actual sale price settles the argument better than a disputed number on paper. Continued co-ownership after divorce is rare anywhere in California and rarer still here.
It takes an unusual degree of post-divorce cooperation to manage a property that may double as a rental during tourist season.
Whichever path is chosen, the tax treatment of any payment one spouse makes to the other matters if the house is sold rather than transferred between spouses. It is also often misunderstood. We cover the actual rule — and the common myth that a buyout payment is taxable income — in our explainer on whether a divorce house buyout is taxable in California.
Separate Property Contributions and the Right to Reimbursement
Not every dollar that went into an Avalon house is automatically split 50/50. Family Code §2640 gives a spouse the right to be reimbursed, without interest, for separate property they can trace into buying community property.
Examples include a down payment from money owned before the marriage, or an inheritance put toward the purchase. Payments that reduced the loan principal also count. Payments of interest, taxes, or insurance don’t qualify. The reimbursement comes off the top before the remaining equity is split equally.
It has to be traced with real records — bank statements, escrow documents, gift letters — not just asserted. Some properties had island fixer-upper costs or periodic capital improvements paid from one spouse’s separate funds.
Think of a new roof, foundation work, or anything tied to the island’s coastal and seismic conditions. In those cases, tracking down the records before the appraisal is often the highest-value step either spouse can take.
Exclusive Use After Separation: Watts Charges and Epstein Credits
It’s common for one spouse to stay in the house after separation while the divorce works through the court. California case law has specific ways to account for that fairly at the end.
Under In re Marriage of Watts (1985), the spouse who moved out can seek a “Watts charge.” This is roughly half of the fair rental value of the home for the period the other spouse lived there alone after separation. It is reimbursed to the community estate.
Under In re Marriage of Epstein (1979), a spouse may have used separate, post-separation income to pay a community debt on the house during that same period. Examples are the mortgage, property taxes, and insurance. That spouse can seek an “Epstein credit” for the other spouse’s share of those payments.
The two often net against each other in the final settlement. One spouse owes a Watts charge for living in the house rent-free. The other owes an Epstein credit for the mortgage payments that kept it out of foreclosure.
On the island, a second home or empty house sitting vacant for months is unusual and easy to notice. So these calculations tend to come up early rather than as an afterthought at the final hearing.
What Happens If Neither Spouse Can Afford to Buy Out the Other
This is more common on Catalina Island than on the mainland. There, refinancing options are broader and more lenders are willing to underwrite the property type.
If neither spouse can qualify to refinance and buy out the other’s share, the court can order the home sold and the proceeds divided. During that process, the homestead exemption may protect part of either spouse’s share of the equity from certain creditor claims.
It does not protect against the other spouse’s community property interest, only against outside creditors. We’ve explained what that exemption actually protects, and what it doesn’t, in our guide to California’s homestead exemption. It’s one of the more commonly misunderstood protections in a divorce-driven sale.
Retirement Accounts Often Get Traded Against the House
A house is rarely the only community asset in play. Retirement accounts built up during the marriage are community property too. They are subject to the same equal-division rule under Family Code §2550. Dividing a 401(k), pension, or similar employer plan generally requires a separate court order.
It’s called a Qualified Domestic Relations Order (QDRO), and it directs the plan administrator to split the account. That process runs on its own timeline, independent of the house. It’s common, and often efficient, to trade one asset against the other.
One spouse keeps a larger share of a retirement account, and the other keeps more equity in the house, or vice versa. But that trade only works if both assets are valued accurately and at roughly the same point in time.
A retirement account’s value and a thinly-traded island house’s value can each shift a lot in the months a contested divorce takes to resolve.
Insurance Availability Can Affect the Appraisal Too
Catalina Island’s wildfire and brush-fire exposure has made standard-market homeowners insurance harder to get in parts of Avalon. That has pushed some owners onto the California FAIR Plan — the state’s insurer of last resort — for basic fire coverage.
Some properties can only get FAIR Plan coverage, or need a difference-in-conditions policy layered on top of it. That makes them a very different asset to insure and finance than a comparable mainland home with standard coverage available. That reality belongs in the conversation before a buyout number gets finalized.
We’ve covered how FAIR Plan coverage interacts with a sale more broadly in our guide to selling a house on the California FAIR Plan.
If the House Doubles as a Rental, the Booking Calendar Needs Attention Too
The property may be actively taking guest reservations under a Transient Rental License. If so, existing bookings don’t simply disappear because the owners are getting divorced or the house is changing hands. Whoever manages the calendar needs to decide this as part of the settlement or the sale agreement.
They can honor bookings through a certain date, or transfer reservation management to the buyer. They can also refund guests and close the calendar before marketing the property. A buyer evaluating the house as a cash-flowing asset will want that question answered before they commit to a price.
A transferable, already-booked season is worth something different than an empty calendar starting from zero.
When Selling Fast Is the Wrong Call
A fast sale isn’t the right answer just because a divorce is emotionally exhausting. Both spouses may be able to cooperate long enough to list the property properly. Island marketing can be slower, since the buyer pool is smaller and more specialized.
Even so, a traditional sale will generally net more than a quick cash transaction. That difference matters more when it’s being split two ways rather than kept by one owner. A fast sale makes more sense when:
- the couple can’t agree on a listing agent
- they can’t agree on showings or access for a property neither wants to maintain from the mainland
- one spouse needs to be bought out of the deal quickly to move forward financially
- a court has ordered a sale on a deadline that a normal island listing timeline can’t meet
If Kids Are Involved, School Logistics Shape the Timeline
Avalon has exactly one public school serving the entire island, Avalon School. Somewhat surprisingly, it’s part of the Long Beach Unified School District, even though Long Beach is a ferry ride away on the mainland. It is not part of a local San Gabriel Valley or Los Angeles-area district.
For divorcing parents, that single-school reality removes a variable that mainland custody plans usually have to negotiate. There’s no competing-district school-choice question. But a custody plan that assumes a parent will move to the mainland has real effects on a child’s schooling.
A move on the mainland wouldn’t create those effects. Courts weighing custody and the timing of a home sale take a child’s school continuity seriously. On an island with one school, that carries more practical weight than in a city with a dozen comparable options nearby.
Financing an Island Property Is Its Own Obstacle
A buyout only works if the spouse keeping the house can actually get a loan against it. Catalina Island properties don’t always fit standard mortgage underwriting the way a comparable mainland home would. Some conventional and government-backed loan programs are more cautious about island, resort-area, and non-standard-access properties.
A lender unfamiliar with Avalon may take longer to underwrite the file than a mainland lender doing a routine refinance. It may also require a specialized appraisal. Get pre-qualified with a lender who has actually closed loans on the island.
Do this before building a settlement timeline around a 30-day refinance that assumes mainland-standard processing speed.
Practical Steps for Avalon Couples Dividing a Home
- Confirm how title is actually held and when the property was acquired relative to the marriage date
- Gather documentation of any separate-property contributions before the appraisal, not after
- Hire an appraiser with specific Catalina Island transaction experience rather than a general county appraiser
- Decide early whether a buyout is realistically financeable before building a settlement around it
- Talk to a family law attorney about how §2640 reimbursement and §2550’s equal-division rule apply to your specific numbers
If a sale is the right path and you want a no-obligation cash offer, Cash Home Buyers CA can provide one. Our Avalon divorce page covers how that process works for island property specifically.
Want to see what other California sellers say about working with us? Find Cash Home Buyers CA on Google for reviews, or call us at (424) 435-2326.