Cash Home Buyers in Bel Air, CA
- Foreclosure, inherited, tenants, damage — we buy it
- Zero fees, zero commissions, zero closing costs
- No obligation — turn the offer down and owe us nothing


Vet Any Cash Buyer Before You Sign
See what a legitimate cash offer on a Bel Air estate looks like, and the proof-of-funds and escrow steps a real buyer can always produce.
“Cash home buyer” covers a wide range of operators, and in a neighborhood like Bel Air, where Movoto’s July 2026 data puts the median list price near $7,624,500 across just 102 active listings, the gap between a legitimate buyer and someone shopping a lead list without funds is larger than almost anywhere else in Los Angeles. Cash Home Buyers CA is a Woodland Hills-based operation, about 25 minutes from Bel Air’s West Gate via Sunset and the 405, and we buy property directly with our own funds rather than trying to line up financing after the fact.
A Neighborhood Laid Out for Privacy, Not Turnover
Alphonzo Bell developed the original Bel-Air Estates tract in 1923 with landscape architect Mark Daniels, running roughly from Nimes Road on the north to Sunset Boulevard on the south, and from Beverly Glen Boulevard on the east to Bel Air Road on the west, reached through the East Gate at Beverly Glen and Sunset or the West Gate at Bellagio and Sunset. Many interior streets are private roads under the Bel-Air Association, which has operated since 1942 to preserve the neighborhood’s residential character, and that structure was built for privacy rather than frequent turnover. In a neighborhood laid out that way, a buyer with real cash and no financing contingency stands out precisely because so few transactions happen here in any given month.
What a Legitimate Cash Buyer Looks Like at This Price Point
- Proof of funds, not just an offer letter. On a multimillion-dollar estate, ask for documented proof of funds before you sign anything. A real buyer can produce it quickly; a wholesaler hoping to flip your contract to someone else usually cannot.
- A local escrow relationship. We open escrow with a licensed Los Angeles County title and escrow company, the same kind that handles retail luxury closings, not an out-of-state shell.
- No mystery inspection contingencies. A cash offer that still carries a 30-day inspection contingency or a financing back-up clause is not really a cash offer — it is a financed offer wearing different language.
- Comfort with hillside and title complications. Bel Air properties often sit behind gated private streets maintained by the Bel-Air Association, active since 1942, and can carry brush clearance requirements tied to the neighborhood’s fire history (484 homes lost in the November 1961 fire, six more in the December 2017 Skirball fire). A buyer who has never handled that should not be pricing your property.
Why Bel Air’s Thin Market Makes Cash Buyers More Relevant
Bel Air’s 2023 population of roughly 7,351 residents is spread across 6.37 square miles, one of the lowest densities in the city, and 85.5 percent of homes here are owner-occupied. That combination — large lots, an established owner base, and few transactions in any given month — means the pool of retail buyers able to qualify for a jumbo loan on a property near the $7.6 million median is genuinely small. A house that needs a full renovation, sits inside a trust, or carries a hillside access issue can wait a very long time for the right financed buyer to appear. A cash buyer removes the financing variable entirely and can move on a timeline the retail market simply cannot match.
Watch for These Red Flags at This Price Point
- Pressure to sign an exclusive agreement before you see proof of funds. A real buyer will show you the money is there before asking you to commit to anything exclusive.
- An offer that seems too high with no comparable sales behind it. On a property near a $7.6 million median, an unrealistically high number with no explanation is usually designed to get a signature, with the price renegotiated down later during “inspection.”
- Reluctance to name the escrow or title company. A legitimate transaction always has a specific, licensed title and escrow company attached from very early on.
How We Price a Bel Air Property
We build our number from recent comparable sales inside the gates when they exist, and from the broader Bel Air, Holmby Hills and Beverly Crest corridor when they do not, adjusted for lot size, hillside grading, renovation needs, and any title, trust or tenancy complication. We are transparent about how we arrived at the number, and there is no obligation to accept it — you can walk away and owe us nothing.
What We Buy
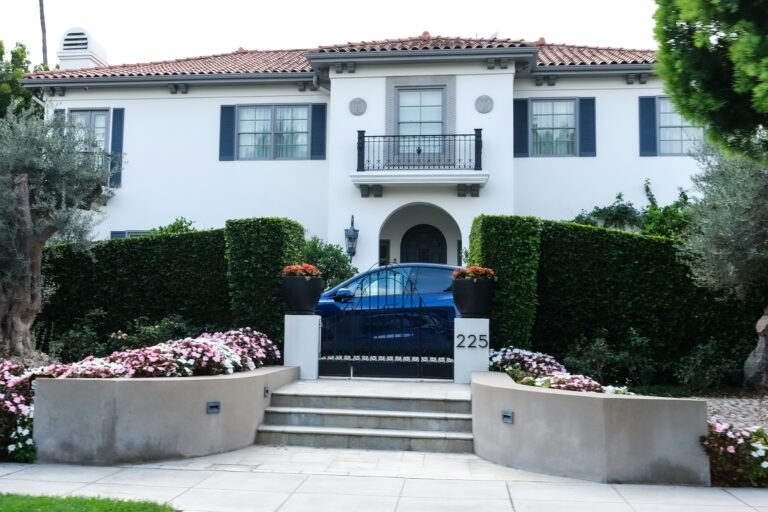
The original Bel-Air Estates tract, laid out by Alphonzo Bell in 1923 with landscape architect Mark Daniels, runs roughly from Nimes Road on the north to Sunset Boulevard on the south, and from Beverly Glen Boulevard on the east to Bel Air Road on the west. We buy across that footprint and the surrounding hills: 1920s and 1930s Mediterranean and Tudor estates, postwar modern houses, and newer construction, in any condition, including inherited estates, houses that need work, and properties with a rented guest house or staff unit in place.
Escrow, Recording and What to Expect
After you accept an offer, we order a preliminary title report and, for a Los Angeles property, the city’s 9A Report of Residential Property Records. Recording happens through the Los Angeles County Registrar-Recorder/County Clerk in Norwalk, and funds are wired the same day the recorder confirms. A clear-title house can close in two to three weeks; an estate in probate through the Stanley Mosk Courthouse, or one with several heirs, typically takes longer, and you set the date. The rules and vetting steps here apply the same way across the rest of the city — see our guide on cash home buyers across Los Angeles for the broader picture.
Why Financed Offers Increasingly Fall Apart at This Price Point
A financed buyer’s offer now depends on more than their loan approval. Since early 2026, several major insurers, including State Farm, Allstate and Farmers, have restricted or stopped writing new homeowners policies in Los Angeles’s highest fire-risk zip codes, and roughly 41 percent of homes in the most exposed zones now rely on the California FAIR Plan, the state’s insurer of last resort. The FAIR Plan alone is rarely enough to satisfy a lender — it excludes water damage, theft and liability, so most jumbo lenders require it paired with a separate difference-in-conditions policy before funding.
On a Bel Air-sized estate, that combined coverage can run $5,000 to $25,000 a year through the FAIR Plan, or $30,000 to $60,000 through a surplus-lines carrier on a larger property. A buyer who waits until late in escrow to shop for coverage can lose weeks, or lose financing altogether if no carrier will bind a policy in time. A cash purchase does not depend on a bound insurance policy to fund, which is one more reason a legitimate cash buyer can close on a timeline a financed retail buyer increasingly cannot guarantee.
Confirm the Escrow Company’s License Before You Sign Anything
Every legitimate real estate transaction in California runs through an escrow holder that is either a licensed escrow company regulated by the California Department of Financial Protection and Innovation, an attorney, or a title company underwritten by an insurer regulated by the California Department of Insurance. Before you sign a purchase agreement on a Bel Air property, ask for the specific escrow company’s name and confirm it independently — by looking it up yourself, not by relying on a number the buyer hands you — rather than assuming any company mentioned is automatically legitimate.
Wire fraud targeting real estate closings has become common enough that title and escrow companies routinely warn clients never to wire funds based on emailed instructions alone. If you are ever asked to wire money as the seller, or to change payoff or payment instructions by email late in escrow, call the escrow company directly at a number you looked up yourself, not one provided in the email, before sending anything.
What Actually Happens Between Acceptance and Funding
Once you accept a written offer, we open escrow with a licensed Los Angeles County title and escrow company the same day, order a preliminary title report, and, for a Los Angeles property, the city’s 9A Report of Residential Property Records. There is no loan file, no appraisal contingency, and no underwriter to satisfy on our side of the transaction, which is the structural reason our timeline does not carry the 45-to-90-day financing risk a retail buyer’s offer does. Funds are wired the same day the Los Angeles County Registrar-Recorder confirms recording, and you choose the closing date within whatever range your situation allows.
Frequently Asked Questions
How do I know your offer is real and not a wholesaler shopping my contract?
Ask for documented proof of funds and the name of the escrow company we plan to use. We will provide both before you sign anything.
Do you buy estates that are still held in a trust?
Yes. We work directly with the trustee and can close on the trust’s timeline, including a court confirmation hearing if the estate is in probate at the Stanley Mosk Courthouse.
Will you lowball a property just because it needs work?
Our offer reflects the property’s actual condition and the comparable sales available, and we explain how we arrived at the number. You are free to decline it.
Do you charge a fee to make an offer?
No. There is never a fee or obligation to get a written cash offer from us.
For a documented, no-obligation cash offer on a Bel Air property, call or text 424-493-4424.
Seller Guides
Helpful guides for homeowners in Bel Air
Plain-English answers to the questions sellers ask us most.
 Inherited homes & probate
Why So Many Arcadia, CA Probate Sales Involve Family Homes
Arcadia's demographic shift since the 1980s made living trusts common, but undeeded trusts still force many inherited Arcadia homes into full probate.
Read the guide →- Foreclosure & liens
The Foreclosure Timeline for an Artesia, CA Homeowner
Artesia homeowners get about 110 days between a recorded Notice of Default and a trustee sale. Here's how California's two waiting periods work.
Read the guide → - Inherited homes & probate
Selling an Inherited House When Citrus, CA Isn’t Actually a City
Citrus, CA has no city government of its own. Here is how that changes permits, code issues, and the probate steps for selling an inherited house there.
Read the guide → - Divorce
Selling the Family Home in a Diamond Bar Divorce: What an HOA Adds to the Process
A Diamond Bar divorce splits community property equally by law, but HOA-governed neighborhoods add an extra disclosure step before closing escrow.
Read the guide → - Selling for cash
What Slows Down a Home Sale in San Fernando, CA
San Fernando is its own independent city inside LA, with its own permits and city hall. Here's what that means for a fast, as-is cash sale today.
Read the guide → - Selling for cash
Sell House Fast Los Angeles: The Real Costs of Each Option
Commissions, iBuyer fees, and holding costs compared to a direct cash sale when selling fast in Los Angeles.
Read the guide → - Selling for cash
We Buy Houses in Los Angeles: How the Process Actually Works
Step by step: how a we buy houses sale works in Los Angeles, from first contact to closing in 7-14 days.
Read the guide → - Selling for cash
We Buy Houses Los Angeles: How to Spot a Legitimate Buyer
Red flags, questions to ask, and what a legitimate we buy houses company in Los Angeles actually looks like.
Read the guide → - Selling for cash
Sell My House Fast Los Angeles: Comparing Your 3 Real Options
List, iBuyer, or direct cash sale - real timelines and tradeoffs for selling a house fast in Los Angeles.
Read the guide →