Trusted Cash Home Buyers in Hancock Park, CA
- Foreclosure, inherited, tenants, damage — we buy it
- Zero fees, zero commissions, zero closing costs
- No obligation — turn the offer down and owe us nothing


Fast, Fair, and Reliable Offers
Looking for a legitimate cash home buyer in Hancock Park? We are a local, direct buyer, not a middleman, and we back every offer with proof of funds.
What Makes a Cash Home Buyer Legitimate
Homeowners in Hancock Park are often approached by wholesalers who lock in a contract and then shop it to other investors before closing. We are different: we are the actual buyer, we fund the purchase ourselves, and we can prove it with documentation before you sign anything.
Large Period Revival Houses
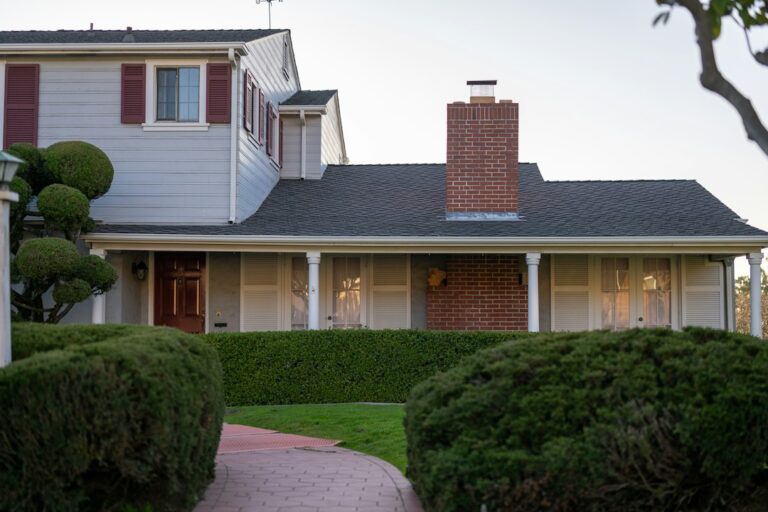
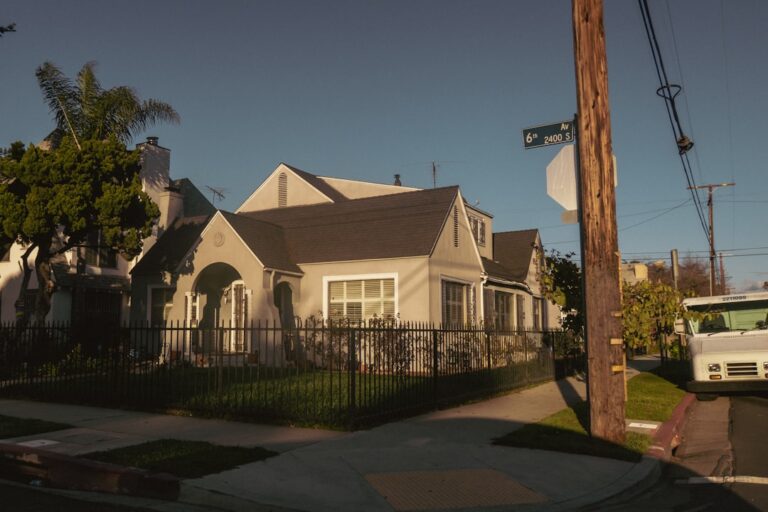
Hancock Park surrounds the Wilshire Country Club and is made up of Tudor, Spanish Colonial, and Mediterranean houses set well back from the street on deep lots. We buy houses across that range, including ones with deferred maintenance or changes that would need historic review.
How We Determine Our Offer
We look at recent comparable sales along with your property’s condition, size, and the repairs a lender would require. We do not quote an unverified neighborhood median; your offer is based on your specific house. We tell you plainly when a traditional listing would likely net you more.
No Games, No Retrading
Once we make an offer and you accept, that is the number we close at. We do not retrade at the last minute or find reasons to lower the price after inspection, since we buy as-is from the start.
How Cash Home Buyers in Hancock Park Actually Work
The phrase cash home buyers covers a wide range of companies, and not all of them work the same way. At its simplest, a cash buyer purchases your house with funds already on hand instead of relying on a mortgage. That one difference changes almost everything about the sale. There is no loan application, no lender-ordered appraisal, and no underwriting delay, so the timeline depends mostly on title, escrow, and the city’s 9A report rather than on a bank.
For Hancock Park sellers, that matters because many houses here are large prewar homes that a lender may look at closely. A cash home buyer in Hancock Park can evaluate the house as it stands, including original systems or past changes, and make one offer based on that. You get a single number, a closing date you choose, and no need to prepare the house for the open market.
How to Vet Any Cash Buyer Before You Sign
Because some companies advertise as buyers but never intend to close themselves, it pays to ask direct questions before signing anything. A few that tend to separate real buyers from middlemen:
- Who is named as the buyer on the contract? It should be the company you are talking to, not a placeholder that can be assigned to someone else.
- Can you show proof of funds? A real cash buyer can typically provide a bank statement or letter showing the money is available.
- Which escrow and title company will you use? A neutral, licensed escrow company should hold the funds and handle the paperwork.
- What contingencies are in the offer? Long inspection periods or vague approval clauses can be a sign the buyer is still looking for someone else to purchase the contract.
- Who pays which costs? Get a clear answer on commissions, escrow fees, and the 9A report up front.
We are happy to answer every one of these in writing. If a buyer avoids them, that is worth noticing.
Selling to a Cash Buyer vs. Listing With an Agent
Neither option is right for every house. A listing puts your home in front of the widest pool of retail buyers, which can bring the highest price for a restored house in move-in condition. The trade-off is time and uncertainty: preparation, showings, negotiation after inspection, and a buyer who may still need loan approval. Agent commission and seller concessions typically come out of your proceeds as well.
Selling to cash home buyers in Hancock Park usually means a lower price than a top retail sale on a perfect house, but it also means no repairs, no commission, no showings, and a closing that does not depend on a lender. For a house that needs work, or for a seller who values a set date over squeezing out the last dollar, the net result is often closer than people expect. We walk through both paths with you honestly.
Houses and Situations We Buy
We buy single-family houses across Hancock Park in a wide range of conditions and circumstances. That includes homes that have been in one family for decades, houses with original kitchens and baths, properties with unpermitted additions or alterations, and houses with tenants in place. We also work with sellers in harder situations, such as an inherited property, a divorce, a relocation, or a pending foreclosure. If you are not sure whether your house fits, a quick call is the easiest way to find out.
Why Condition Matters Less to a Cash Buyer
In a retail sale, condition drives almost every step. A buyer’s inspector writes up each issue, the buyer asks for credits or repairs, and the lender’s appraiser may require certain items fixed before funding. With a Tudor, Spanish Colonial, or Mediterranean house built in the 1920s, that list can be long, and some exterior fixes on a contributing house may need historic review before anyone can touch them. A cash buyer prices those items in at the start instead of negotiating them one by one near the end. That is why an older Hancock Park house with deferred maintenance is often a better fit for a cash sale than for a listing, and why our offer does not move after the walkthrough.
What the Process Looks Like
It starts with a short conversation about the house and your timeline. We then look at the property, review recent comparable sales, and consider its condition and any historic-overlay factors. You receive a written, no-obligation offer. If you accept, escrow opens, title is ordered, and we request the 9A report. You choose the closing date, and your proceeds are paid out once the deed records. For a closer look at each step, see our Hancock Park cash offer process.
Costs You Avoid When Selling for Cash
A direct sale strips out several expenses that are common in a traditional sale. There is no agent commission. There are no pre-listing repairs, staging, or cleaning bills. There are no credits negotiated after a buyer’s inspection, and no months of mortgage, insurance, taxes, and utilities while the house sits on the market. On our purchases we also take on the 9A report and retrofit certifications. The city and county transfer tax still applies to any sale, and we explain exactly how it is handled on your closing statement.
Why Hancock Park Owners Work With Us
Owners here tend to want a buyer who understands older, larger houses and the historic overlay, and who will not change the deal after the fact. We are the direct buyer, we explain how we reach our number, and we tell you when listing is the smarter move. To talk with one of our cash home buyers about your Hancock Park property, call or text 424-493-4424.
Frequently Asked Questions
Are you the actual buyer or a middleman?
We are the direct buyer. We fund the purchase ourselves and can provide proof of funds.
Do you buy houses in the historic overlay zone?
Yes. We confirm a house’s contributing status and prior approval history early in escrow ourselves.
How do you calculate your offer?
We use recent comparable sales along with your property’s condition and size.
Will the price change after you inspect the house?
No. Because we buy as-is, the offer we make is the offer we close at.
Do you charge any fees or commissions?
No. You do not pay a commission when you sell directly to us, and we explain every line of the closing statement before you sign.
Who holds the money during the sale?
A neutral escrow company holds the funds and releases them once the deed records, so neither side handles the money directly.
How soon can I get an offer?
Usually shortly after we talk and see the house. The offer is written, carries no obligation, and you can take as long as you need to decide.
Selling a house in Hancock Park: what to know
A few local details that shape timing and net proceeds when you sell in Hancock Park.
County & probate court
Hancock Park is a City of Los Angeles neighborhood in Los Angeles County. Probate and trust matters for Hancock Park properties are heard by the Superior Court for Los Angeles County, and deeds are recorded with the Los Angeles County Recorder.
Transfer tax
Los Angeles County charges a documentary transfer tax of $1.10 per $1,000 of the sale price. The City of Los Angeles adds $4.50 per $1,000, and Measure ULA adds 4% on sales above roughly $5 million (5.5% above roughly $10 million). When you sell to us, we pay the standard closing costs.
Tenant & rent rules
Rental homes in Hancock Park can fall under the Los Angeles Rent Stabilization Ordinance (RSO), which limits rent increases and requires just cause for most evictions, in addition to the statewide Tenant Protection Act (AB 1482). We buy tenant-occupied homes and take over the leases at closing.
Nearby cities we buy in
Seller Guides
Helpful guides for homeowners in Hancock Park
Plain-English answers to the questions sellers ask us most.
 Inherited homes & probate
What the Hancock Park HPOZ Means for a Probate Sale
Inheriting a Hancock Park house? See how California probate works and what the neighborhood's historic HPOZ requires before any exterior work.
Read the guide →- Selling as-is
As-Is Home Sale Disclosure Rules in North El Monte, CA
North El Monte isn't the City of El Monte. As-is disclosure duties are the same statewide, but its permit records run through LA County, not a city hall.
Read the guide → - Relocating
Relocating From Altadena, CA After the Eaton Fire
The Eaton Fire destroyed 9,419 structures in Altadena. Homeowners relocating can carry their old property tax base to a new home anywhere in California.
Read the guide → - Divorce
Selling the Family Home in a Diamond Bar Divorce: What an HOA Adds to the Process
A Diamond Bar divorce splits community property equally by law, but HOA-governed neighborhoods add an extra disclosure step before closing escrow.
Read the guide → - Selling for cash
What Slows Down a Home Sale in San Fernando, CA
San Fernando is its own independent city inside LA, with its own permits and city hall. Here's what that means for a fast, as-is cash sale today.
Read the guide → - Selling for cash
Sell House Fast Los Angeles: The Real Costs of Each Option
Commissions, iBuyer fees, and holding costs compared to a direct cash sale when selling fast in Los Angeles.
Read the guide → - Selling for cash
We Buy Houses in Los Angeles: How the Process Actually Works
Step by step: how a we buy houses sale works in Los Angeles, from first contact to closing in 7-14 days.
Read the guide → - Selling for cash
We Buy Houses Los Angeles: How to Spot a Legitimate Buyer
Red flags, questions to ask, and what a legitimate we buy houses company in Los Angeles actually looks like.
Read the guide → - Selling for cash
Sell My House Fast Los Angeles: Comparing Your 3 Real Options
List, iBuyer, or direct cash sale - real timelines and tradeoffs for selling a house fast in Los Angeles.
Read the guide →