
Dividing a House in an Avalon, CA Catalina Divorce
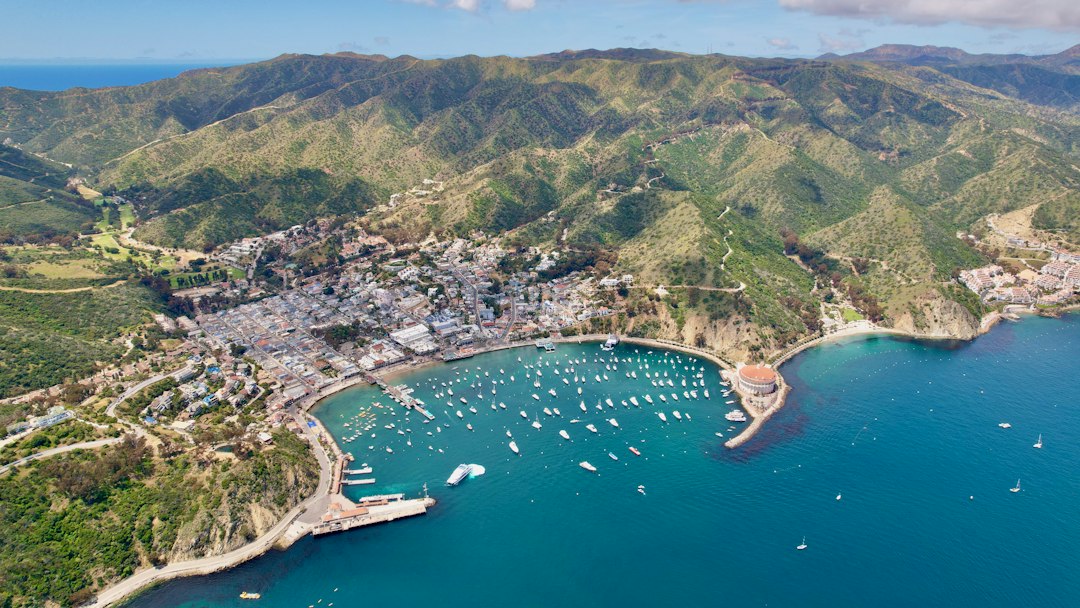
California divides community property equally in a divorce, but “equally” gets complicated fast when the asset in question is a house on an island with roughly 3,460 year-round residents and almost no comparable sales to appraise against. Avalon is the only incorporated city on Santa Catalina Island, reachable only by ferry, helicopter, or small aircraft, and its housing market behaves nothing like the mainland cities this same law applies to everywhere else in the state. If you’re dividing a home here, our Avalon divorce page covers the local sale process; this piece covers the community property rules driving the decision in the first place.
California Is a Community Property State — What That Means Here
Family Code §760 defines community property broadly: all property, real or personal, acquired by a married person during the marriage while domiciled in California is community property, regardless of whose name is on the title. A house bought during the marriage with community funds is community property even if only one spouse’s name appears on the deed. Family Code §2550 then requires the court to divide the community estate equally between the spouses upon dissolution, unless the parties agree in writing (or stipulate in open court) to something different. For a single asset like a house, “equally” usually means one of three outcomes: sell it and split the proceeds, have one spouse buy out the other’s interest, or — less commonly — continue to co-own it under a post-divorce agreement.
The general rules governing who keeps the house and how the split is calculated apply the same way in Avalon as anywhere else in California; we’ve laid out the baseline mechanics in our guide to who gets the house in a California divorce. What’s different in Avalon is almost everything downstream of that baseline rule.
Why an Island Housing Market Complicates an Equal Division
Equal division depends on knowing what the house is worth, and that’s harder to pin down in a city of roughly one square mile of developed land than almost anywhere else in the county. Avalon’s housing stock is small, much of it dates to the early 20th century, and a meaningful share of transactions involve vacation or investment buyers rather than the kind of owner-occupant comparables an appraiser would use on the mainland. Inventory is thin enough that in a given month there may be only a handful of recent closed sales to draw from, and the tourism-driven economy — the city draws roughly a million visitors a year — means some of what looks like comparable housing stock is actually short-term rental or commercial-adjacent property that doesn’t appraise the same way. Divorcing couples here often need a certified appraiser with specific Catalina Island experience, not a general Los Angeles County appraiser pulling from mainland comps, and even then the appraisal is more of an informed estimate than the tight range a dense suburban market would produce.
Short-Term Rental Licenses Add a Wrinkle Most Appraisers Miss
A meaningful share of Avalon housing stock operates as a vacation rental, and the city regulates that use tightly enough that it can directly affect what a divorcing couple’s house is actually worth. Under the city’s transient rental ordinance, operating a rental for stays under 30 days requires a Transient Rental License, and the city caps the combined total of Transient Rental Licenses, Conditional Use Permits, and grandfathered Conditional Use Permits at 410 units citywide — once that cap is reached, new applicants go onto a waitlist or lottery rather than simply applying and receiving one. A License is generally non-transferable except in a single one-time transfer to immediate family, and an existing Conditional Use Permit is automatically lost upon the property’s second sale. If the house being divided already carries one of these licenses or permits, that income-producing status is a real asset — but depending on how many times the property has already changed hands and how the eventual transfer is structured, it may not survive a sale to a third party the way either spouse assumes. This is worth confirming with the city before an appraisal or settlement locks in a value that assumes rental income the next owner may not actually be able to collect.
Buyout, Sale, or Co-Ownership: The Three Paths
A buyout — one spouse keeping the house and paying the other half of the net equity, often by refinancing or trading other community assets of equivalent value — is the cleanest path when both spouses want it and one can actually qualify to refinance a Catalina Island property, which not every mainland lender is set up to do. A straight sale and split of proceeds is usually the simplest path when neither spouse wants to keep the house, or when thin island inventory means the appraised value is uncertain enough that an actual sale price resolves the argument better than a disputed number on paper. Continued co-ownership after divorce is rare anywhere in California and rarer still here, since it requires an unusual degree of post-divorce cooperation to manage a property that may double as a rental during tourist season.
Whichever path is chosen, if the house is sold rather than transferred between spouses, the tax treatment of any payment one spouse makes to the other matters and is frequently misunderstood. We cover the actual rule — and the common misconception that a buyout payment is taxable income — in our explainer on whether a divorce house buyout is taxable in California.
Separate Property Contributions and the Right to Reimbursement
Not every dollar that went into an Avalon house is automatically split 50/50. Family Code §2640 gives a spouse the right to be reimbursed, without interest, for separate property they can trace into the acquisition of community property — a down payment from money owned before the marriage, an inheritance put toward the purchase, or payments that reduced the loan principal (though not interest, taxes, or insurance payments, which don’t qualify). The reimbursement comes off the top before the remaining equity is split equally, and it has to be traced with real records — bank statements, escrow documents, gift letters — not just asserted. On a property where island fixer-upper costs or periodic capital improvements (a new roof, foundation work, anything tied to the coastal and seismic conditions specific to the island) were paid from one spouse’s separate funds, tracking down those records before the appraisal is often the highest-value step either spouse can take.
Exclusive Use After Separation: Watts Charges and Epstein Credits
It’s common for one spouse to stay in the house after separation while the divorce works through the court, and California case law has specific mechanisms for accounting for that fairly at the end. Under In re Marriage of Watts (1985), the spouse who moved out can seek a “Watts charge” — roughly half of the fair rental value of the home for the period the other spouse occupied it exclusively after separation, reimbursed to the community estate. Under In re Marriage of Epstein (1979), a spouse who used separate, post-separation income to pay a community debt — the mortgage, property taxes, insurance — on the house during that same period can seek an “Epstein credit” for the other spouse’s share of those payments. The two often net against each other in the final settlement: one spouse owes a Watts charge for living in the house rent-free, while the other owes an Epstein credit for the mortgage payments that kept it out of foreclosure. On an island property where a second home or empty house sitting vacant for months is unusual and conspicuous, these calculations tend to surface early rather than being an afterthought at the final hearing.
What Happens If Neither Spouse Can Afford to Buy Out the Other
This is more common on Catalina Island than on the mainland, where refinancing options are broader and more lenders are willing to underwrite the property type. If neither spouse can qualify to refinance and buy out the other’s share, the court can order the home sold and the proceeds divided, with the homestead exemption potentially protecting a portion of either spouse’s share of the equity from certain creditor claims during the process — not from the other spouse’s community property interest, but from outside creditors. We’ve explained what that exemption actually protects, and what it doesn’t, in our guide to California’s homestead exemption, since it’s one of the more commonly misunderstood protections in a divorce-driven sale.
Retirement Accounts Often Get Traded Against the House
A house is rarely the only community asset in play, and retirement accounts accumulated during the marriage are community property subject to the same equal-division rule under Family Code §2550. Dividing a 401(k), pension, or similar employer plan generally requires a separate court order called a Qualified Domestic Relations Order (QDRO) directing the plan administrator to split the account, and that process runs on its own timeline, independent of the house. It’s common, and often efficient, for one spouse to keep a larger share of a retirement account in exchange for the other spouse keeping more equity in the house, or vice versa — but that kind of trade only works if both assets are valued accurately and at roughly the same point in time, since a retirement account’s value and a thinly-traded island house’s value can each shift meaningfully in the months a contested divorce takes to resolve.
Insurance Availability Can Affect the Appraisal Too
Catalina Island’s wildfire and brush-fire exposure has made standard-market homeowners insurance harder to secure in parts of Avalon, pushing some owners onto the California FAIR Plan — the state’s insurer of last resort — for basic fire coverage. A property that can only get FAIR Plan coverage, or that needs a difference-in-conditions policy layered on top of it, is a meaningfully different asset to insure and finance than a comparable mainland home with standard coverage available, and that reality belongs in the conversation before a buyout number gets finalized. We’ve covered how FAIR Plan coverage interacts with a sale more broadly in our guide to selling a house on the California FAIR Plan.
If the House Doubles as a Rental, the Booking Calendar Needs Attention Too
If the property is actively taking guest reservations under a Transient Rental License, existing bookings don’t simply disappear because the owners are getting divorced or the house is changing hands. Whoever manages the calendar needs to decide, as part of the settlement or the sale agreement, whether to honor bookings through a certain date, transfer reservation management to the buyer, or refund and close the calendar before marketing the property — and a buyer evaluating the house as a cash-flowing asset will want that question answered before they commit to a price, since a transferable, already-booked season is worth something different than an empty calendar starting from zero.
When Selling Fast Is the Wrong Call
A fast sale isn’t the right answer just because a divorce is emotionally exhausting. If both spouses can cooperate long enough to list the property properly — even with the slower pace island marketing sometimes requires, since the buyer pool is smaller and more specialized — a traditional sale will generally net more than a quick cash transaction, and that difference matters more when it’s being split two ways rather than kept by one owner. A fast sale makes more sense when the couple can’t agree on a listing agent, can’t agree on showings or access logistics for a property neither wants to maintain from the mainland, when one spouse needs to be bought out of the deal quickly to move forward financially, or when a court has ordered a sale on a deadline that a normal island listing timeline can’t meet.
If Kids Are Involved, School Logistics Shape the Timeline
Avalon has exactly one public school serving the entire island, Avalon School, which somewhat surprisingly operates as part of the Long Beach Unified School District rather than a local San Gabriel Valley or Los Angeles-area district, despite Long Beach being a ferry ride away on the mainland. For divorcing parents, that single-school reality removes a variable that mainland custody arrangements usually have to negotiate — there’s no competing-district school-choice question — but it also means a custody arrangement that assumes a parent will relocate to the mainland has real consequences for a child’s schooling that a mainland move wouldn’t create. Courts weighing custody and the timing of a home sale take a child’s school continuity seriously, and on an island with one school, that consideration carries more practical weight than it would in a city with a dozen comparable options nearby.
Financing an Island Property Is Its Own Obstacle
A buyout only works if the spouse keeping the house can actually get a loan against it, and Catalina Island properties don’t always fit standard mortgage underwriting the way a comparable mainland home would. Some conventional and government-backed loan programs are more conservative about island, resort-area, and non-standard-access properties, and a lender unfamiliar with Avalon specifically may take longer to underwrite the file or require a specialized appraisal than a mainland lender processing a routine refinance. It’s worth getting pre-qualified with a lender who has actually closed loans on the island before building a settlement timeline around a 30-day refinance that assumes mainland-standard processing speed.
Practical Steps for Avalon Couples Dividing a Home
- Confirm how title is actually held and when the property was acquired relative to the marriage date
- Gather documentation of any separate-property contributions before the appraisal, not after
- Hire an appraiser with specific Catalina Island transaction experience rather than a general county appraiser
- Decide early whether a buyout is realistically financeable before building a settlement around it
- Talk to a family law attorney about how §2640 reimbursement and §2550’s equal-division rule apply to your specific numbers
This is general information about California community property law, not legal advice specific to your case; consult a family law attorney before relying on any of it for a settlement. If a sale is the right path and you want a no-obligation cash offer, Cash Home Buyers CA can provide one, and our Avalon divorce page covers how that process works for island property specifically.