
Who Gets Credit for the Down Payment on an Agua Dulce Ranch in a Divorce
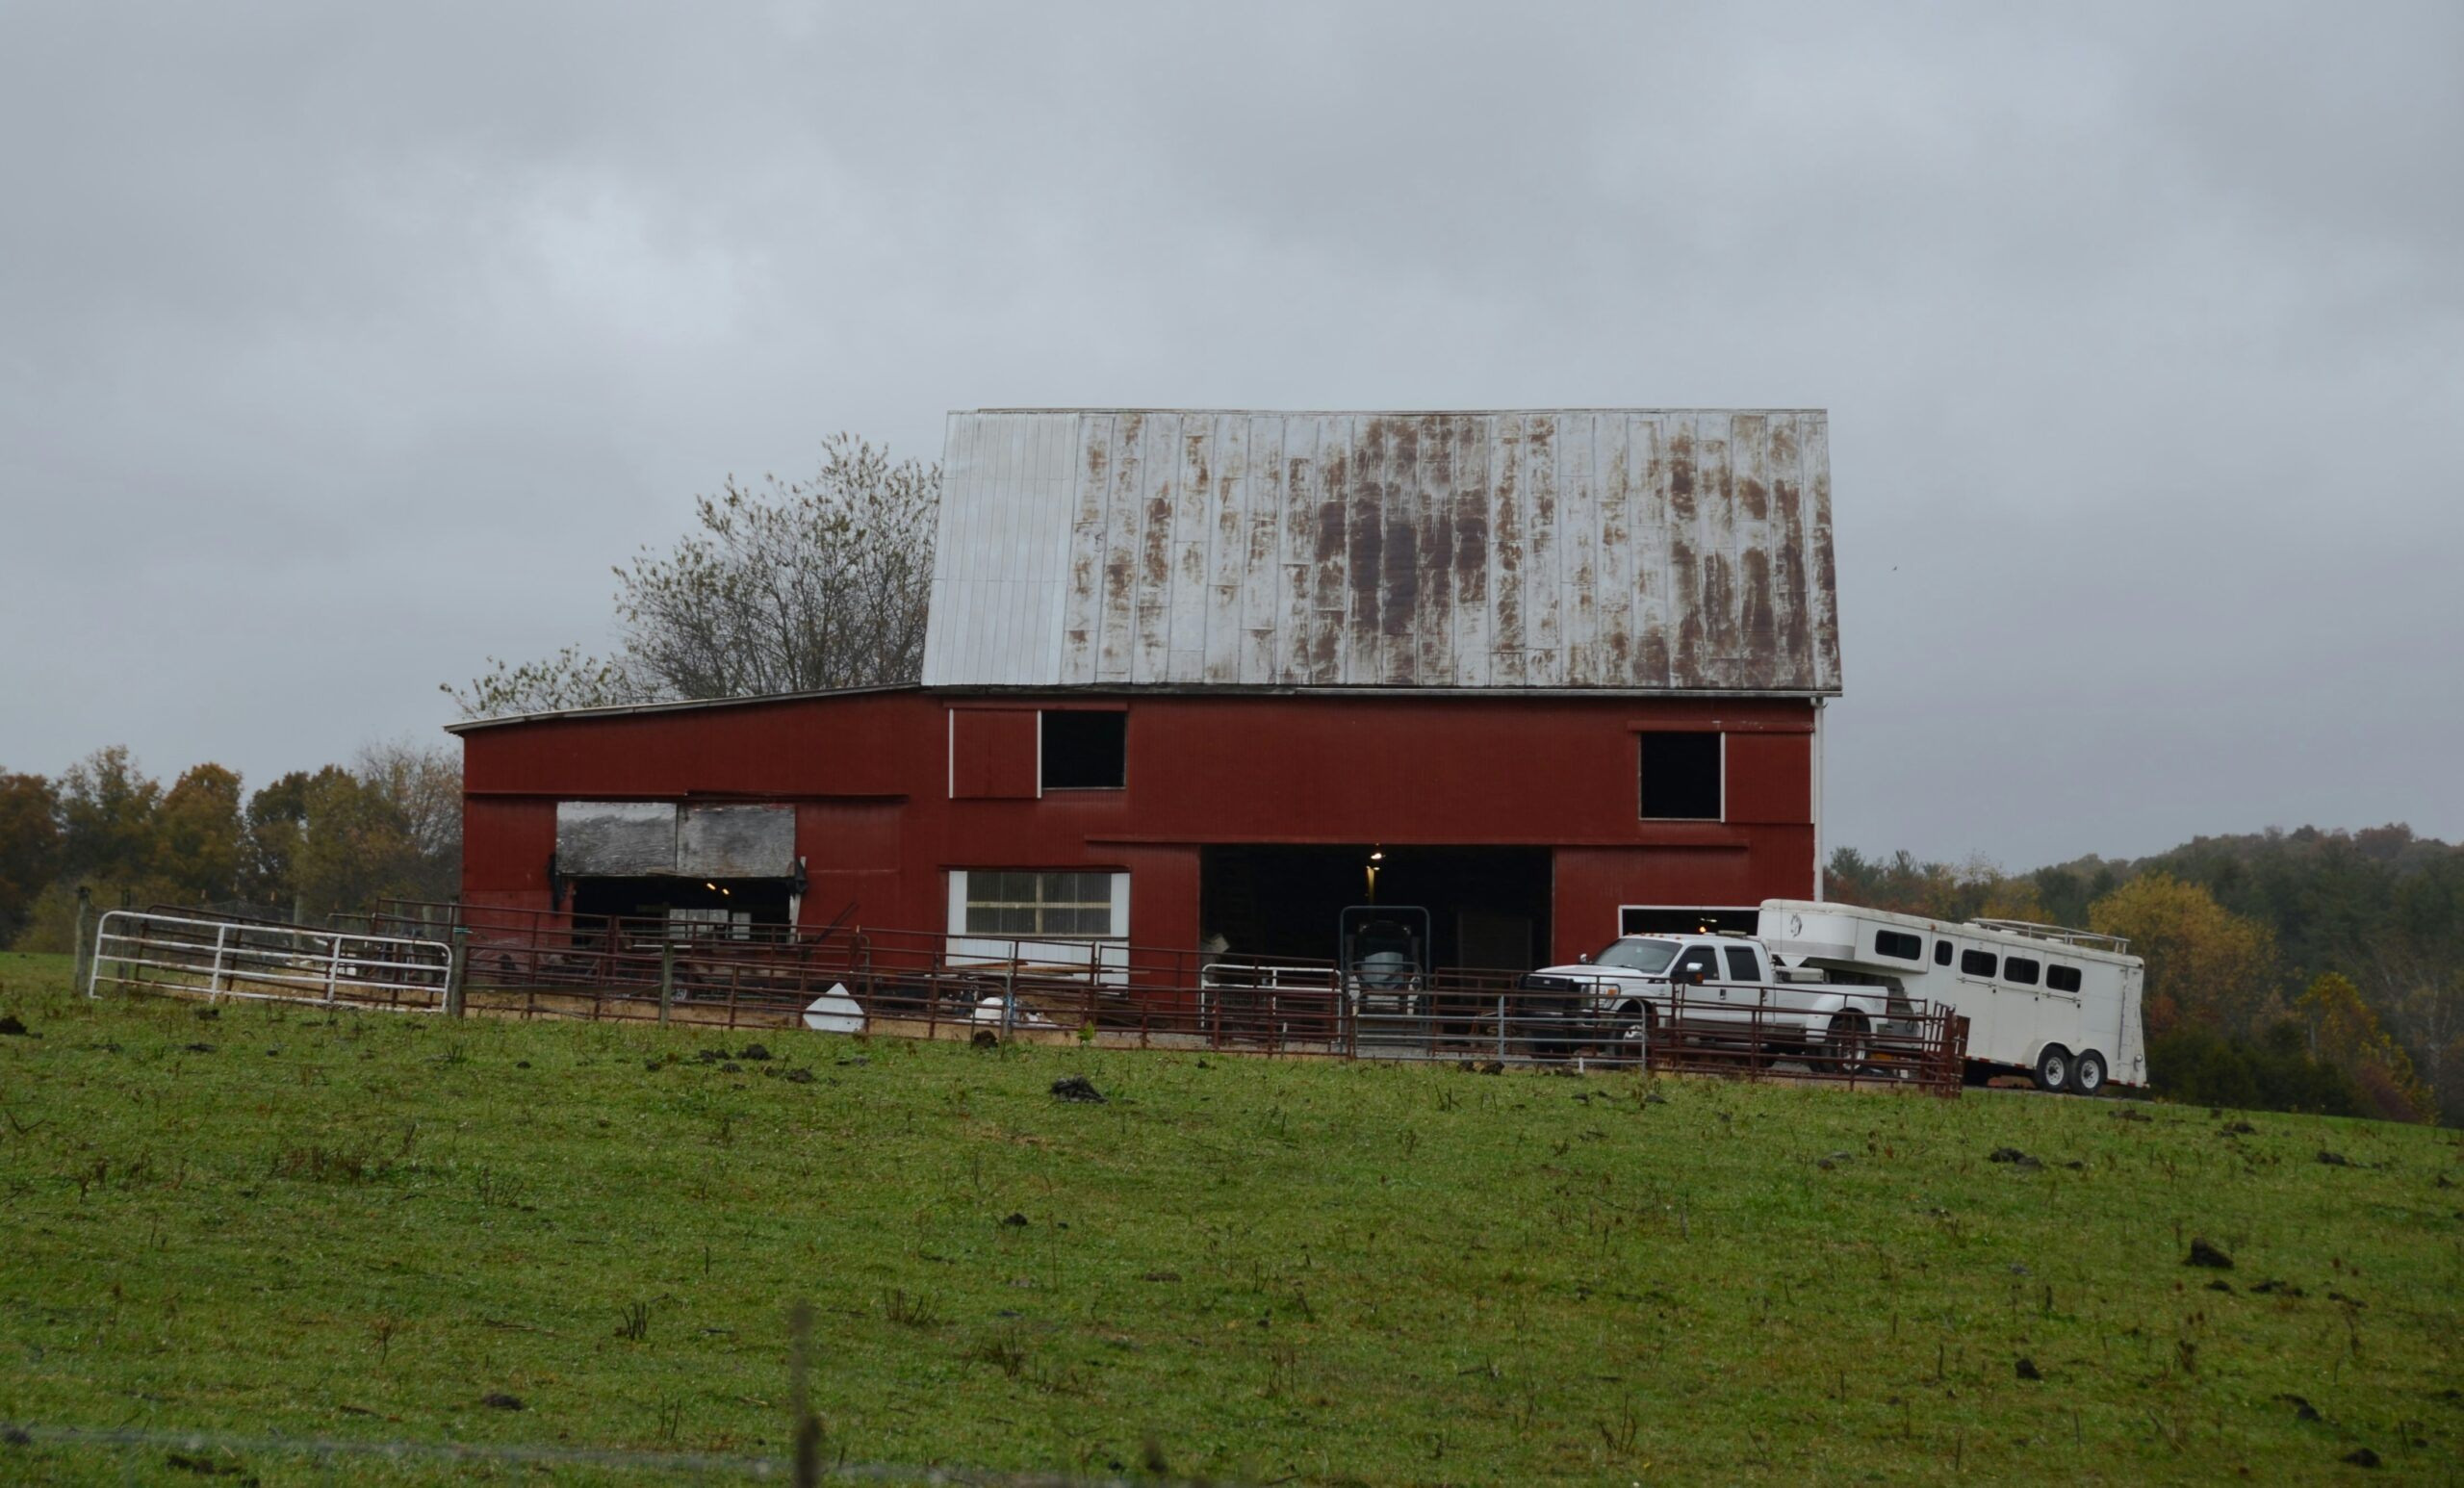
The spouse who put separate-property funds into the down payment on a jointly titled home is entitled to get that exact dollar amount back before the rest of the equity is split — not a bigger ownership share, just a dollar-for-dollar reimbursement off the top. California Family Code §2640 guarantees this, but only if the contribution can be traced to a separate source and was never waived in writing. In Agua Dulce, where many homes sit on larger equestrian parcels rather than standard subdivision lots, getting that reimbursement right often turns on a valuation question before it turns on a legal one.
Agua Dulce is an unincorporated community in Los Angeles County — a Census Designated Place (ZIP 91390) in the Sierra Pelona Valley near Vasquez Rocks, with a 2020 Census population of 3,451. It has a distinctly rural, equestrian character: a 2023 estimate puts median household income around $124,268, and the homeownership rate runs near 86.4%, well above what you’d see in a typical tract-home suburb. Larger-acreage horse properties, not cookie-cutter lots, are the norm here, and that shapes how a divorce-related home sale or buyout actually plays out.
This article walks through how California divides a home that was bought during the marriage, titled jointly, but partly funded by one spouse’s separate money — the down payment scenario that comes up constantly in divorces involving horse property, where one spouse often brought savings, an inheritance, or proceeds from a previously owned property into the purchase. If you’re past the legal analysis and ready to talk about actually selling the house, our page on selling a house during divorce in Agua Dulce, CA covers that process directly. This piece stays on the question underneath it: who gets credit for what was put in, and how much — starting with the default rule that makes §2640 necessary in the first place, moving through how a separate contribution gets traced and reimbursed, why the valuation side is harder on acreage with a barn than on a tract lot, and when a court — rather than the spouses themselves — ends up deciding to sell.
The Default Rule: It’s Community Property
California Family Code §760 sets the baseline: property acquired by either spouse during the marriage is presumed to be community property, regardless of whose name appears on the title or who wrote the checks. A home bought during the marriage and titled in both spouses’ names is community property by default, even if one spouse alone made every mortgage payment or supplied the entire down payment from money earned before the wedding.
That presumption can be overcome, but it takes more than a memory of who paid for what. It takes a paper trail. Without one, the law simply treats the Agua Dulce property — house, barn, arena, and all — as community property to be divided equally, full stop.
There’s a related rule worth knowing about: when spouses take title in a joint form — both names on the deed, as joint tenants or as community property — California law presumes the property is community property for division purposes, even if one spouse can show they personally funded the purchase. Overcoming that joint-title presumption generally requires a clear written statement in the deed or a separate agreement, not just testimony about where the money came from. That’s precisely why §2640 matters so much in practice: a spouse usually can’t argue their way back into separate ownership of a jointly titled home, but they can still recover the specific dollars they put in. The separate-property contribution only gets that legal weight once it’s documented and traced, which is the next step.
Tracing a Separate-Property Down Payment
“Tracing” means connecting specific dollars that went into the down payment back to a separate-property source — money owned before the marriage, an inheritance, a gift, or proceeds from the sale of a separate-property asset — through bank records, escrow statements, and account histories. A spouse who says “I put $120,000 down from my inheritance” needs more than a recollection; they need the inheritance documentation, the account it landed in, and a line showing that money moving into escrow.
Two things can defeat a reimbursement claim before the tracing even gets evaluated. First, commingling: if the separate funds sat in a joint account for years, mixed with community income, before the down payment was made, tracing can become difficult or impossible depending on the account records available. Second, a written waiver: if the spouse who contributed the separate funds signed anything — often buried in loan or escrow paperwork — stating they waived the right to reimbursement, §2640 reimbursement is off the table regardless of how clean the tracing otherwise is. Both issues come up often enough in practice that an attorney should review the actual documents before anyone assumes a contribution is recoverable.
A typical scenario looks like this: one spouse sold a condo they owned before the marriage, deposited the proceeds directly into an escrow account tied to the Agua Dulce purchase, and that same escrow closed on the ranch within weeks. That’s a relatively clean trace — a direct line from separate asset to down payment, with no intervening joint account to muddy the source. Contrast that with a spouse who deposited an inheritance into a joint checking account years before the home purchase, used that account for groceries and bills alongside the inherited funds, and then wrote a check for the down payment from the same commingled account. In the second scenario, a forensic accountant may still be able to trace the funds using accounting methods courts accept, but it takes real analysis rather than a bank statement anyone can read at a glance — and the outcome is less certain going in.
What §2640 Actually Reimburses — and What It Doesn’t
Once tracing is established and no waiver exists, §2640 entitles the contributing spouse to reimbursement for three specific categories: the down payment, improvements to the property, and payments that reduced the loan principal. The reimbursement is dollar-for-dollar — no interest accrues on it, and it is not adjusted for inflation even if the contribution was made many years before the divorce. It also cannot exceed the home’s net value at the time of division; if the property’s equity has fallen since the contribution was made, the reimbursement is capped at whatever net value remains.
Just as important is what the statute leaves out. Mortgage interest, property taxes, homeowners insurance, and routine maintenance paid during the marriage are not reimbursable under §2640, even if one spouse paid all of it from separate funds. Those are treated as ordinary community expenses — the kind of cost the law assumes a couple shares as part of living together — and no credit is given for them at division. So a spouse who covered the down payment and later also paid years of property tax bills on an Agua Dulce ranch can expect reimbursement for the down payment portion, but not for the tax payments layered on top of it.
To see how the math actually works, imagine a home with $500,000 in net equity at the time of divorce, where one spouse traced a $60,000 separate-property down payment with clean documentation and no waiver. That spouse receives $60,000 off the top — no interest added for the years that have passed, no inflation adjustment — leaving $440,000 in community equity to split under whatever the marital settlement agreement or court order provides, commonly an even split. If the home’s net equity had instead fallen to $45,000 by the time of division, the reimbursement would be capped at that $45,000, and there would be nothing left over to divide as community equity at all. The reimbursement right is real, but it’s bounded by what the property is actually worth net of debt on the date it matters, not by what the original contribution would be worth today.
And the reimbursement itself doesn’t change who owns what. It doesn’t give the contributing spouse 60% of the house instead of 50%. It simply comes off the top of the sale or buyout proceeds before the remaining equity is split between the spouses under the usual community-property rules.
Why Horse Property Complicates the Appraisal
Because the §2640 reimbursement cap is tied directly to the home’s net value at division, an accurate valuation matters more here than in most divorce house situations — and Agua Dulce’s rural, equestrian-oriented properties are genuinely harder to value quickly than a standard subdivision home. A larger-acreage parcel with a barn, a riding arena, a hay barn, or a separate guest structure doesn’t appraise the way a three-bedroom tract house does; comparable sales are thinner, and an appraiser needs to separate what’s real property (the land, the house, permanently attached structures) from what isn’t.
Horses themselves, along with tack, trailers, and some freestanding outbuildings, may be personal property rather than part of the real estate appraisal at all — which means they get valued and divided separately from the land and home, under their own rules, rather than folded into the real-property number that drives the §2640 calculation. Getting this split wrong in either direction — treating personal property as part of the house, or missing real property improvements that were built with separate funds — can throw off both the reimbursement calculation and the community-equity split that follows it.
In practice, this usually means a qualified appraiser familiar with rural and equestrian properties, not just a generic residential appraisal, is worth the extra time and cost before either spouse agrees to a number. A quick, informal valuation that treats an Agua Dulce ranch like a standard house risks producing a net-value figure that won’t hold up if either side disputes the reimbursement amount later.
There’s also a timing issue specific to larger acreage: fewer truly comparable sales close in any given stretch of months on Sierra Pelona Valley horse properties than close on a standard subdivision street, which can mean waiting longer for a defensible set of comps or paying for an appraiser to adjust more heavily for differences in acreage, outbuildings, and improvements. Neither spouse benefits from rushing this step — a reimbursement calculation built on a shaky valuation is one that tends to get challenged later, which costs more time and money than getting it right the first time.
When the Court Can Order a Sale
Once the reimbursement is calculated and the remaining community equity is identified, the spouses can divide it however their marital settlement agreement specifies — commonly through a buyout, where one spouse refinances and pays the other their share, or through a sale with proceeds split after the §2640 amount is paid out. If the spouses can’t agree on either path, California Family Code §§2552 and 2554 give the family court authority to order the property sold and the proceeds divided, rather than leaving the house in limbo indefinitely.
Courts generally don’t want to force a sale when spouses can work out a buyout between themselves — a court-ordered sale is more often what happens after negotiation has stalled, or when neither spouse can afford to buy the other out and keeping the property in limbo isn’t realistic. On an Agua Dulce property with horses that need daily care, that stalemate carries real-world costs beyond the legal ones, which is often what eventually pushes one or both spouses toward a faster resolution.
When Selling for Cash Isn’t the Right Move
A fast cash sale is not the right answer for every divorce involving a house, and it’s worth saying so plainly. If one spouse genuinely wants to keep the Agua Dulce property — the horses, the barn, the land they’ve invested in — and can qualify to refinance the mortgage into their name alone and buy out the other spouse’s share, that buyout usually serves both spouses better than a sale to a third party. Nobody has to leave a property they’re attached to, and nobody loses the upside of continued appreciation.
If both spouses are willing to cooperate and there’s no pressing deadline — no looming foreclosure, no court order forcing a quick resolution, no urgent need for liquidity — listing the property on the open market with a real estate agent will often net a better price than a quick cash sale, especially for a distinctive equestrian property where the right buyer pool matters. Rural and horse-property buyers are a specific market, and a traditional listing with proper marketing time can reach them in a way a rushed sale cannot.
And if the separate-property tracing itself is contested — one spouse disputes that the down payment was truly separate, or the paper trail is incomplete — that’s a reason to pause before selling, not a reason to rush. Selling the property first and sorting out the reimbursement afterward can make tracing and valuation harder, not easier, since the evidence needed to establish the separate contribution and the home’s net value at the relevant time can become more difficult to pin down once the property has changed hands. A forensic accountant and a family law attorney should weigh in on the tracing question before either spouse commits to a sale timeline.
Practical First Steps
- Gather the escrow statements and bank records from when the home was purchased, so the down payment source can actually be traced
- Check loan and escrow paperwork for any written waiver of reimbursement rights before assuming §2640 applies
- Hire an appraiser experienced with rural and equestrian properties rather than a generic residential appraisal
- Separate personal property — horses, tack, trailers, movable outbuildings — from the real property valuation early
- Talk to a family law attorney about whether a buyout, a traditional sale, or a court-ordered sale fits your situation before committing to any one path
For the broader question of who ends up with the house in a California divorce more generally, see Who Gets the House in a Divorce in California? And if a buyout is on the table instead of a sale, it’s worth understanding the tax side first — Is a House Buyout in a California Divorce Taxable? walks through that.
This article is general information, not legal advice — talk to a California family law attorney about your specific situation, especially where tracing or valuation is disputed. If you’ve worked through the legal and valuation questions and decide a sale is the right path, Cash Home Buyers CA can provide a no-obligation cash offer, and our page on selling a house during divorce in Agua Dulce, CA covers what that process looks like locally.