
California’s Mills Act: How the Historic-Property Tax Contract Actually Works
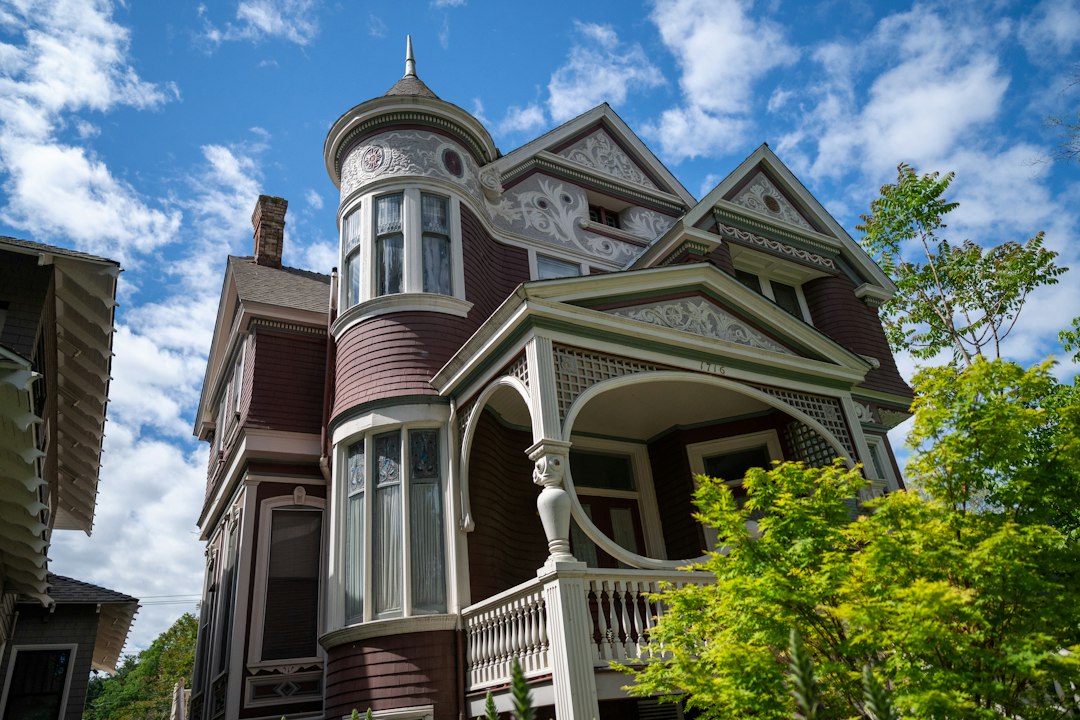
If you own a historic home in California, or are thinking about buying one, there is a property tax program that can cut your assessed value far below what Proposition 13’s standard factored-base-year approach would produce, with nothing to do with a change in ownership or an assessment appeal.
It is called the Mills Act, it predates Prop 13 itself, and it works by a different method than almost any other property tax rule in the state: instead of taxing the home at what it is worth on the market, the county values it based on what it could earn as a rental, capitalized into a present value.
For the right historic property the gap between those two numbers can be substantial, which is why the program attracts both genuine preservationists and buyers shopping for a historic home specifically for the tax treatment that comes with it.
The Mills Act is not automatic, it does not apply the same way everywhere, and it carries real strings attached once you sign. How the contract works, who has to approve it, and what it costs to exit matters whether you are an owner weighing whether to apply, an heir who inherited a property that already has one, or a buyer about to take one over.
A Different Kind of Property Tax Break
The program comes from the Government Code, Article 12, Sections 50280 through 50290, enacted in 1972, with a companion assessment method set out in Revenue and Taxation Code Sections 439 through 439.4.
It lets a city or county enter into a contract with the owner of a qualified historic property under which the owner commits to preserving and maintaining the building, and in exchange the county assessor values the property using the income approach rather than the standard market approach most California property uses.
That distinction is the entire point of the program. A normal Prop 13 assessment values a property at its purchase price or construction cost, adjusted upward by no more than 2% a year until the next change in ownership resets it.
A Mills Act contract instead has the assessor estimate what the property could reasonably earn in rent, based on comparable rents for a residential property or actual rent received for a commercial one, then divide that income figure by a capitalization rate to arrive at the assessed value.
In a market where land and construction costs have pushed sale prices far above what a building could rent for, that income-based number can land well below either the market value or the Prop 13 factored value the property would otherwise carry.
What You Have to Give Up to Get It
The tax benefit is not free. A Mills Act contract runs for a minimum term of ten years, and the owner agrees to restore, maintain, and protect the property according to historic preservation standards written into the contract and the local jurisdiction’s own guidelines.
Most participating cities and counties conduct periodic inspections, and the contract binds whoever owns the property for as long as it is in effect, not just the person who signed it.
That maintenance obligation is where owners run into trouble years later.
A Mills Act contract is not a one-time application that quietly reduces your tax bill with no further obligation; it is an ongoing commitment the jurisdiction can and does check on, usually tied to the Secretary of the Interior’s Standards for Rehabilitation or a comparable local ordinance, which can limit what exterior changes or material substitutions you are allowed to make without running afoul of the contract.
How the Assessor Values a Mills Act Property
The assessor is not simply picking a lower number; the statute requires a specific formula built around the income the property could generate.
For an owner-occupied residential property, the assessor looks at what comparable properties in the area rent for, even though the owner is not actually renting out their own home, and treats that hypothetical rental income as the basis for the calculation.
That figure is then divided by a capitalization rate set under the statute and adjusted periodically, converting a stream of hypothetical rental income into a present assessed value.
The practical effect is that a Mills Act assessment moves with rental-market conditions and capitalization rates rather than with sale prices, which is part of why it can diverge so sharply from both the home’s market value and the Prop 13 factored value a long-time owner might already be enjoying.
Neither the state Office of Historic Preservation nor the statute itself publishes a standard percentage savings figure, since the result depends on the specific property, its location, and the rental and capitalization-rate data in effect that year, so treat any savings percentage you see quoted online as an estimate, not a guarantee, for your own property.
Not Every City or County Participates
The Mills Act is a local option, not a statewide entitlement.
The state enables the program and keeps records of the ordinances, resolutions, and contracts that participating jurisdictions adopt, but each city or county decides for itself whether to run a program at all, and if it does, sets its own criteria for which properties qualify and how many contracts it will allow active at once.
Cities with large historic housing stocks, Los Angeles, Pasadena, Long Beach, and San Diego among them, run active, well-documented programs. Others have never adopted an ordinance, meaning there is no mechanism to apply there no matter how historic the property is.
Do not assume the program is available in your area just because a neighboring jurisdiction offers it. Confirm directly with the local planning or community development department whether a program exists, what its application cycle looks like, and whether it is currently accepting new contracts, since some jurisdictions cap active contracts and periodically close applications once that cap is reached.
The Contract Follows the House, Not the Owner
One detail that surprises buyers and heirs more than almost anything else about this program: the contract is tied to the property, not the person who signed it.
When a Mills Act home sells, the existing contract transfers to the new owner along with the property, with the same remaining term, maintenance obligations, and inspections.
A buyer cannot opt out simply by declining to re-sign anything, and a seller cannot unilaterally cancel it just because they are listing the home.
For an heir, this means a contract a parent or grandparent signed years ago is still binding after the property passes through probate or a trust distribution, and the preservation obligations do not pause during that transition. If you are not interested in continuing them, look at the formal exit mechanisms described below rather than assuming the obligation lapses when ownership changes hands.
Walking Away From the Contract the Easy Way
The statute gives both the owner and the local government a built-in way to let a Mills Act contract run out instead of renewing indefinitely. Under Government Code Section 50282, each contract automatically adds one year to its term on its anniversary date unless a party serves written notice of nonrenewal.
An owner who wants out must serve that notice at least 90 days before the renewal date; the local government, if it is declining to continue, must serve its notice at least 60 days before that date.
Once served, the contract does not end immediately; it runs out for the balance of whatever term remained from its original execution or last renewal, which, given the ten-year minimum term, usually means several more years of the existing tax treatment and obligations before it actually expires.
This path matters most for long-range planning, since it lets an owner begin the wind-down clock well before needing the obligations to end, rather than being locked into indefinite renewal with no exit short of a breach-based cancellation.
If the local government serves nonrenewal on its own initiative, the owner has the right to file a written protest, and the jurisdiction can withdraw its notice any time before the renewal date.
What Counts as a Qualified Historic Property
Not every older home qualifies.
The statute defines a qualified historical property as privately owned, not otherwise exempt from property taxation, and meeting one of two tests: listed in the National Register of Historic Places or located within a registered historic district, or listed on a state, city, county, or combined city-and-county official register of historically or architecturally significant sites, places, or landmarks.
In practice this usually means the property carries a formal individual landmark designation, sits inside a locally adopted historic overlay district, or is independently listed on the National Register, rather than simply being an old building that looks historic.
Because that register requirement varies so much by jurisdiction, the application process almost always starts with the local planning department confirming eligibility before any tax benefit is discussed, and many cities require the historic designation itself to be finalized, sometimes through its own separate hearing process, before a Mills Act application can even be submitted.
Breaking the Contract the Hard Way
Nonrenewal is the clean exit. Breach is not.
If a city or county’s legislative body determines an owner has breached any contract condition, or allowed the property to deteriorate past the standard for a qualified historical property, Government Code Section 50284 requires the jurisdiction to either cancel the contract through the notice-and-hearing procedure in Sections 50285 and 50286, or bring a court action for specific performance or an injunction instead of canceling outright.
If cancellation is the route taken, Section 50285 requires a public hearing before the contract can be canceled, with notice mailed to the owner and published under the state’s general notice statute.
If the cancellation goes forward, Section 50286 imposes a fee equal to 12.5% of the property’s current fair market value, determined by the assessor as though the property were free of the Mills Act restriction, payable to the county auditor and distributed across the taxing jurisdictions the same way the annual tax increment is.
That fee is calculated against current, unrestricted market value, not the lower Mills Act assessed value the owner had been paying taxes on, which is why a breach-based cancellation is a far more expensive way to exit the program than the nonrenewal process above.
The Paperwork Doesn’t End at Signing
Because the tax savings are tied to an ongoing obligation rather than a one-time event, participating jurisdictions typically build in some periodic check, whether a scheduled inspection, a photo-documentation requirement, or a renewal-time self-certification.
An owner who lets deferred maintenance pile up, or makes an exterior alteration without the required review, is not just risking an ordinary code-enforcement issue; they are risking the specific finding of deterioration or breach that triggers the Section 50284 cancellation process above.
If you inherited a Mills Act property and are not sure what condition it must be kept in, request a copy of the actual recorded contract from the county recorder or the city’s planning department rather than relying on a general sense of what “historic preservation” means.
The contract spells out the specific conditions you are bound by, and those conditions are what any future inspection or renewal decision will be measured against.
Why Lenders and Title Companies Ask About It
A recorded Mills Act contract runs with the land, so it shows up in a title search the same way an easement or recorded covenant would, and both lenders and title companies treat it as something to account for rather than ignore.
A lender financing a Mills Act purchase may ask for documentation that the contract is in good standing, since a pending breach-cancellation proceeding or deterioration finding could affect the property’s value.
A title company will typically disclose the recorded contract to the buyer as an exception to title, which is routine, but it means the contract cannot be quietly overlooked during a transaction.
Buyers sometimes assume a Mills Act contract is pure financial upside with no due diligence required, since the headline is “lower property taxes.” The fuller picture is that the buyer is also taking on a recorded, locally enforceable obligation to maintain the property to a specific preservation standard for however many years remain on the contract.
When a Cash Sale Is the Wrong Move Here
A Mills Act contract, treated honestly, is rarely a reason by itself to sell quickly or at a discount.
The contract transfers to the next owner automatically, buyers who want a historic home with favorable tax treatment actively seek these properties out, and the lower assessed value tends to make the home more attractive to a knowledgeable buyer, not less.
If your only issue is that you own a well-maintained historic property and are simply ready to move on, a standard listing, marketed with the tax benefit as a selling point, will typically net more than a direct cash sale, since nothing about the contract makes the property harder to finance or insure while in good standing.
A cash sale makes more sense when the property comes bundled with a harder problem: deferred maintenance serious enough that the jurisdiction could plausibly find a breach or deterioration, an unresolved code-enforcement history, a probate timeline that needs to close quickly, or a buyer pool that is hard to finance conventionally because of the property’s age or condition.
There, a buyer who can close fast and take on the property and its preservation obligations as part of the purchase can be worth more than holding out for a retail buyer while the compliance issue sits unresolved.
First Steps
- Confirm whether your city or county actually runs a Mills Act program before assuming the tax benefit is available, since adoption is a local decision and not every jurisdiction participates.
- Request a copy of the recorded Mills Act contract from the county recorder or local planning department if you inherited or are buying a property that has one, rather than relying on a general understanding of what it requires.
- Ask the local planning or historic preservation office directly whether the property is currently in compliance before you rely on the existing tax assessment continuing unchanged.
- If you want out of the contract on your own terms, calendar the 90-day owner notice-of-nonrenewal deadline under Government Code Section 50282 well in advance of the contract’s renewal date.
- Before financing or insuring a Mills Act property, confirm with your lender and title company how they are treating the recorded contract as part of underwriting and title review.
- If deferred maintenance or a compliance question is unresolved, address it or get a clear answer from the jurisdiction before listing, since a pending deterioration finding is the kind of issue a buyer’s lender and title company will want explained.
The Mills Act can be one of the more valuable property tax tools available to a California homeowner, but it is a negotiated, recorded, ongoing obligation rather than a one-time discount, and it rewards owners who understand exactly what they signed and what it would take to get out of it cleanly.
If you inherited a historic property with a Mills Act contract attached, or you are untangling one alongside probate, deferred maintenance, or a compliance question you would rather not carry into a sale, Cash Home Buyers CA can make a no-obligation cash offer and work through the existing contract as part of closing.
If you are weighing whether to sell a Southern California property that already carries one of these contracts, our guide on selling a house with an existing Mills Act contract walks through the transaction side in more detail, and our posts on the Prop 19 parent-child exclusion deadline and on carrying your tax base to a new home after 55 cover two of the other California property-tax programs that often intersect with a historic-property sale. You can also find Cash Home Buyers CA on our Google Business listing.