
Stop Foreclosure in Eastside Costa Mesa, CA
- Foreclosure, inherited, tenants, damage — we buy it
- Zero fees, zero commissions, zero closing costs
- No obligation — turn the offer down and owe us nothing


Protect Your Equity Before the Auction Date
See California’s statutory foreclosure timeline and how a direct sale can protect your equity before an Eastside Costa Mesa trustee’s sale.
Foreclosure in California moves faster than most homeowners expect, and Eastside Costa Mesa’s high property values raise the stakes on how much equity is on the line. Cash Home Buyers CA buys houses in pre-foreclosure throughout Eastside Costa Mesa, and this page walks through the statutory timeline and where a sale can still protect your equity.
Eastside Costa Mesa sits against the Newport Beach line, with the 17th Street corridor running through it and easy access to the 55, 73, and 405 freeways and John Wayne Airport, and its housing stock ranges from original 1940s and 1950s cottages to newer contemporary rebuilds. That mix means a house behind on payments here can look very different from one town over, and it affects how quickly a sale can move.
California’s Foreclosure Timeline
Most California mortgages use a deed of trust, which lets a lender foreclose without going through court. The process starts with a Notice of Default, recorded after payments have been missed for a period set by the loan documents, typically around 90 days delinquent.
After the Notice of Default records, state law requires at least a three-month waiting period before the lender can record a Notice of Trustee’s Sale, which sets the date, time, and location of the auction.
Once that notice records, there is a minimum of 20 days before the sale can actually occur.
Added together, a homeowner in Eastside Costa Mesa has a minimum of roughly three months and 20 days from the recorded Notice of Default to the earliest possible trustee’s sale date, though lenders often take longer in practice.
Your Right to Reinstate
Up until five business days before the scheduled trustee’s sale, a homeowner generally has the right to reinstate the loan by paying the missed payments, late fees, and foreclosure costs to bring the account current, without paying off the full loan balance.
After that window closes, the only way to stop the sale is to pay the loan off in full or reach another agreement with the lender. Selling the property before that late-stage deadline is often the more realistic path once reinstatement funds are not available.
Why Equity Matters More in Eastside Costa Mesa
Redfin’s trailing three-month data through August 2026 shows a median sale price of $1,949,059 in Eastside Costa Mesa, with 55 homes sold and a median of 53 days on market.
At that price level, even an owner behind on payments for months usually has substantial equity, since the loan balance is often well below current value.
A trustee’s sale wipes out that equity for the borrower — any proceeds above what is owed at auction are handled through a separate, often slow, surplus funds process, so selling before the auction is generally the more direct way to capture that value yourself.
Junior Liens and HELOCs
A second mortgage or home equity line of credit does not disappear in a foreclosure on the first mortgage, and it has to be accounted for at payoff whether the sale happens through escrow or at auction.
Most Eastside Costa Mesa parcels carry no HOA, so there is typically no HOA lien to add to that list, but any recorded judgment or tax lien against the property still has to be resolved before or at closing.
Options Before the Trustee’s Sale
- Reinstate the loan. Pay what is past due before the five-business-day cutoff if funds are available.
- Negotiate a loan modification or forbearance. Some lenders will adjust terms, though this depends entirely on the specific lender and loan type.
- Sell the property. A sale that closes before the trustee’s sale date pays off the loan through escrow and lets you keep the remaining equity directly, rather than waiting on a post-auction surplus claim.
- Short sale. If the loan balance exceeds what the house is worth, a lender-approved short sale is possible, though that scenario is uncommon given current Eastside Costa Mesa values.
The Notice of Default Itself
The Notice of Default is a public record, filed with the Orange County Clerk-Recorder in Santa Ana, and it names the amount owed and the lender pursuing the foreclosure.
Because it is public, it is also why homeowners in pre-foreclosure often start getting mail and calls from investors soon after it records — not because anyone tipped anyone off, but because the filing itself is searchable.
That is worth knowing so a legitimate outreach does not feel more alarming than it needs to be, though it is still worth verifying anyone you talk to the same way you would vet any cash buyer.
How a Cash Sale Fits the Foreclosure Timeline
We can typically make a written offer within 24 to 48 hours of hearing from you, and because there is no lender-ordered appraisal or loan underwriting to wait on, we can often close in two to three weeks on a house with clear enough title to record.
That timeline fits inside the roughly four-month window between a Notice of Default and a trustee’s sale, even when the notice of sale has already been recorded, as long as there is enough time left before the auction date.
Our full cash-offer process for Eastside Costa Mesa covers escrow and recording in detail, and the same statutory timeline applies to a property anywhere else in Costa Mesa.
What the House’s Condition Does Not Change
An original 1940s or 1950s Eastside Costa Mesa cottage behind on payments often also needs deferred maintenance the owner has not had funds to address. We buy the property as-is, so there is no repair list to complete before closing, which matters when time before the trustee’s sale is limited. See our page on selling as-is in Eastside Costa Mesa for more detail on how that works.
When Foreclosure Overlaps With Other Situations
A pending foreclosure sometimes runs alongside an inherited property where the original owner passed away with a mortgage still in place, or a divorce where neither spouse can keep up payments alone. Each situation adds its own steps on top of the foreclosure timeline, and it is worth reviewing the one that matches your circumstances.
Comparing a Trustee’s Sale to a Direct Sale
At a trustee’s sale, bidding typically starts at the amount owed on the loan plus foreclosure costs, and the property is sold as-is to the highest bidder, often an investor bidding without ever stepping inside.
At the current Eastside Costa Mesa median of $1,949,059, the gap between a typical loan balance and current market value can be substantial, and that gap is exactly what a homeowner risks losing at auction versus capturing through a direct sale that closes before the sale date.
A direct sale also gives you control over the closing date, whereas a trustee’s sale happens on the date set in the recorded notice regardless of your circumstances.
Recording and Payoff
Once you accept an offer, escrow opens with an Orange County title company, which orders a payoff statement directly from your lender and pays it off from sale proceeds at closing. The deed records at the Orange County Clerk-Recorder in Santa Ana, and any remaining equity after payoff, liens, and Orange County’s $1.10 per $1,000 documentary transfer tax is wired to you the same day recording is confirmed.
How to Stop Foreclosure in Eastside Costa Mesa Before the Auction
To stop foreclosure in Eastside Costa Mesa, one of three things has to happen before the trustee sale: the default is cured, the servicer agrees to a workout, or the loan is paid off. The options, side by side:
- Reinstatement. Paying the past-due amount plus allowed fees and costs; generally available until five business days before the sale.
- Loss mitigation. A repayment plan, forbearance or modification if your income supports a payment going forward.
- Bankruptcy. A filing can pause a sale; a bankruptcy attorney can say whether it fits.
- Selling first. Escrow pays off the loan and any junior liens, and the remaining equity goes to you.
HUD-approved housing counseling agencies offer free or low-cost help with servicer negotiations, and reaching one early keeps more of these options open.
Stopping Foreclosure by Selling vs. Waiting for the Auction
| Factor | Cash sale before the auction | Listing while in default | Trustee sale |
|---|---|---|---|
| Timeline | Often two to three weeks with clear title | Market time plus a 30 to 45 day financed escrow | Set by the recorded notice |
| Repairs | None required | Often requested by buyer or lender | Not applicable |
| Commissions | None to you | Often around 5 to 6 percent combined | None, but no control over price |
| Your equity | Paid to you at closing after liens and costs | Paid to you if escrow closes in time | Any surplus must be claimed separately |
| Certainty | No loan or appraisal contingency | A late loan denial can miss the sale date | Proceeds unless cured, postponed or paid off |
Why the Calendar Matters at These Prices
Redfin’s data for the three months ending August 2026 shows homes in Eastside Costa Mesa taking about 53 days to sell, up from 36 a year earlier.
Add a financed escrow and a listing can run past a sale date that is roughly three months and 20 days from the Notice of Default at the legal minimum. A cash closing is built around the date on your Notice of Trustee’s Sale.
If you are also dealing with a divorce or an estate, our guide to the Eastside Costa Mesa cash offer process shows how escrow handles several signers. Call or text 424-435-2326 as soon as you have a sale date.
Frequently Asked Questions
How fast can I stop foreclosure in Eastside Costa Mesa by selling?
With clear title, a cash sale can often close about two to three weeks after you accept an offer. Escrow pays the loan off at closing, which ends the foreclosure, so call as soon as you know the sale date.
What is the minimum foreclosure timeline in California?
At least three months must pass after the Notice of Default before a Notice of Trustee’s Sale can be recorded, and that notice must be posted and published at least 20 days before the auction.
Where can Eastside Costa Mesa homeowners get free foreclosure help?
HUD-approved housing counseling agencies offer free or low-cost help with repayment plans, forbearance and loan modification requests. For bankruptcy or a disputed default, talk with a California attorney.
How long do I have before a trustee’s sale in California?
At minimum, about three months after a Notice of Default records before a Notice of Trustee’s Sale can be recorded, plus at least 20 more days before the sale itself — roughly four months total, though lenders often take longer.
Can I still reinstate my loan close to the sale date?
Generally yes, up until five business days before the scheduled sale, if you can pay the missed amount plus fees.
What happens to my equity if the house goes to auction?
Any surplus above what is owed is handled through a separate post-sale claims process, which is typically slower than receiving proceeds directly through an escrow closing.
Can you close before my trustee’s sale date?
Often yes, since we do not require lender underwriting or an appraisal, but the sooner you reach out, the more time there is to work with.
Do I need to repair the house before selling it in foreclosure?
No. We buy the property as-is, regardless of its condition.
Where does the Notice of Default get recorded?
At the Orange County Clerk-Recorder in Santa Ana, which is also why it becomes a public, searchable record soon after filing.
Get a free, no-obligation cash offer from Cash Home Buyers CA today.
Seller Guides
Helpful guides for homeowners in Eastside Costa Mesa
Plain-English answers to the questions sellers ask us most.
 Rentals & tenants
Which Mountain View Rentals Does the CSFRA Actually Cover?
See which Mountain View rentals the CSFRA covers, its rent cap, just-cause eviction rules, relocation pay, and what landlords must do before raising rent.
Read the guide → Foreclosure & liens
The 90-Day Window That Can Block Your California Home Sale: Mechanics Liens
A mechanics lien can block your California home sale. Here's the 90-day deadline to record, foreclose, and clear it before escrow closes.
Read the guide → Foreclosure & liens
How an HOA Can Actually Foreclose on a California Home (and the Deadlines That Protect You)
California HOA liens aren't super-priority, but can foreclose in 75 days. See the delinquency, notice, and 90-day redemption rules that apply.
Read the guide → Foreclosure & liens
Is California a Judicial or Nonjudicial Foreclosure State?
California allows judicial foreclosure, but almost every lender chooses nonjudicial. Here's why, and what it means for deficiency and redemption rights.
Read the guide → Foreclosure & liens
Foreclosure Surplus Funds in California: The Money Left on the Table
California law entitles former owners to leftover funds after a foreclosure sale, but claiming them is slow and often targeted by recovery scams.
Read the guide → Foreclosure & liens
What Is a Notice of Default in California?
A Notice of Default starts California foreclosure. Learn the reinstatement deadline, the 3-month timeline, and your options before a sale date is set.
Read the guide → Foreclosure & liens
Short Sales in California: The Deficiency Protection Most Sellers Miss
California law usually waives your lender's right to sue for the difference after a short sale. Here's how that deficiency protection works.
Read the guide →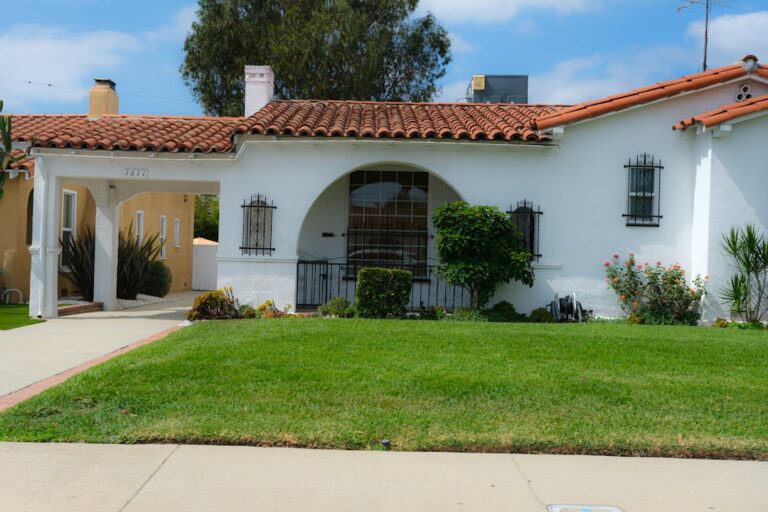 Foreclosure & liens
Selling a House With a Reverse Mortgage in California
You can sell a house with a reverse mortgage in California, but heirs face a tight HUD deadline and a fast, non-judicial…
Read the guide → Foreclosure & liens
Deed in Lieu of Foreclosure in California: The Real Rules
A deed in lieu can stop foreclosure, but deficiency protection isn't automatic in California. See exactly what to negotiate before you sign anything.
Read the guide →