
Trusted Cash Home Buyers in Harbor City, CA
- Foreclosure, inherited, tenants, damage — we buy it
- Zero fees, zero commissions, zero closing costs
- No obligation — turn the offer down and owe us nothing


Fast, Fair, and Reliable Offers
Looking for a legitimate cash home buyer in Harbor City? We can buy directly or bring in a vetted cash buyer, and we back every offer with proof of funds.
What Makes a Cash Home Buyer Legitimate
Homeowners in Harbor City are often approached by buyers who lock in a contract and then assign it to other investors before closing. Whoever you talk to, ask who will take title, and ask for documentation of funds before you sign anything. We can provide proof of funds on request.
Houses, Condos, and Small Buildings
Harbor City has a real mix of single-family houses, condo units, and small apartment buildings. We buy across that whole range — including condos in HOAs that a traditional lender might balk at financing, since we don’t need lender approval to close.
How We Determine Our Offer
We look at recent comparable sales — Homes.com’s trailing 12-month data (September 2026) shows a median sale price around $800,000 in Harbor City, with single-family houses running closer to $910,000 — along with your property’s condition, size, and any repairs needed, to arrive at a fair cash number.
No Games, No Retrading
Once we make an offer and you accept, that’s the number we close at. We don’t retrade at the last minute or find reasons to lower the price after inspection, since we buy as-is from the start.
Working With Cash Home Buyers in Harbor City: How It Works
Searching for cash home buyers in Harbor City usually turns up a long list of names, signs on telephone poles, and postcards in the mailbox. They are not all the same kind of business. Some are direct buyers who purchase and hold or renovate properties themselves.
Others are marketers who sign a contract and then try to sell that contract to someone else. Knowing the difference before you sign anything can save you weeks of waiting and a deal that falls apart at the last minute.
When you work with us, the process is simple. You tell us about the property, we see it in person, and we give you a written cash offer. If you accept, we open escrow with a neutral title or escrow company, and we close on a date you choose. You are dealing with the buyer from the first conversation to the last signature.
Questions to Ask Any Cash Buyer Before You Sign
A few straightforward questions will tell you a lot about who you are dealing with. We encourage Harbor City homeowners to ask them of every company they talk to, including us:
- Are you the buyer named on the contract? If the contract lists the buyer as a company and assigns, the paper may be sold to someone you have never met.
- Can you show proof of funds? A real cash buyer can typically provide a bank statement or letter showing the money is available.
- Which escrow or title company will you use? A legitimate sale runs through an independent escrow holder, not through the buyer’s own account.
- What contingencies are in the contract? Long inspection periods or vague approval clauses can give a buyer an easy way to walk away or ask for a lower price.
- Who pays the closing costs? Get the answer in writing, not just on the phone.
Cash Buyer vs. Listing With an Agent
Listing with an agent is a good choice for some sellers, especially when the house is updated and there is no rush. A financed buyer on the open market may pay more for a move-in-ready home. That path usually comes with a commission, preparation costs, showings, and a buyer whose loan must clear an appraisal and underwriting before closing.
A cash sale trades some of that potential upside for certainty. There is no lender, so there is no appraisal gap and no financing contingency. There are no showings beyond a walkthrough.
You typically do not pay a commission, and the timeline is set by you rather than by a mortgage company. For a lot of Harbor City sellers dealing with an older house, a condo with HOA complications, a tenant, or a tight deadline, that trade makes sense.
What We Buy Around Harbor City
As a direct buyer, we look at a wide range of property types and conditions across Harbor City. That includes single-family houses, condo and townhome units, and small apartment buildings. We regularly consider homes that are:
- Dated or in need of major repairs
- Inherited, in probate, or held in a trust
- Occupied by a tenant with an existing lease
- Behind on payments or facing a notice of default
- Part of a divorce or separation
- Owned by someone who has already moved away
If you are not sure whether your property fits, ask. There is no cost to find out.
What Happens After You Accept Our Offer
Once you accept, we send the signed agreement to escrow. The escrow officer orders a preliminary title report, requests the payoff for any existing mortgage, and prepares the closing documents. If the property is a condo, the HOA documents are collected during escrow. Our team keeps you updated along the way so you are never left wondering where things stand.
At closing, you sign the deed and settlement paperwork, the loan is paid off from the proceeds, and the balance goes to you. If you want to see each stage laid out in more detail, our Harbor City cash offer process page walks through it step by step.
Costs You Typically Avoid Selling to a Direct Buyer
Every sale has some costs, but a direct sale removes many of the ones sellers dread most.
You typically avoid agent commissions, pre-listing repairs, staging and cleaning, and the carrying costs that pile up while a house sits on the market, such as the mortgage payment, insurance, utilities, and HOA dues.
Because we buy as-is, you also avoid the back-and-forth repair requests that often follow a buyer’s inspection. If you have questions about how the sale affects your taxes, your CPA is the best person to ask.
What to Have Ready When You Call
You do not need a folder of documents to get an offer, but a few details help us move faster.
It is useful to know the property address, roughly how many bedrooms and bathrooms it has, whether anyone is living there, and any major issues you are aware of, such as a leaking roof or an older electrical system.
If there is a mortgage, an approximate balance helps us understand your situation. If the house is part of an estate or a divorce, let us know who is authorized to sign. Missing information is fine; we can sort it out together as we go.
Why Harbor City Homeowners Choose Us as Their Cash Buyer
Homeowners who choose a local cash home buyer in Harbor City usually want the same few things: a fair number, a straight answer, and a closing date they can count on. That is what we focus on.
We explain how we arrived at our offer, we put the terms in writing, and we do not pressure anyone to sign. If our offer does not work for you, you are free to walk away.
To get started, call or text 424-435-2326 or use the form at the top of this page.
Frequently Asked Questions
How do I know a cash home buyer in Harbor City is legitimate?
Ask for proof of funds, confirm they are the buyer named on the contract, and make sure the sale runs through an independent escrow company. A legitimate buyer will be comfortable answering all three.
Do I have to accept your offer?
No. Every offer is no-obligation. You can take time to review it, ask questions, or compare it with other options.
Can you buy a house that is occupied?
Yes. We buy houses and units with tenants in place, and we can also work with owners who are still living in the home and need time to move.
Who will take title at closing?
We can buy your house directly or bring in a vetted cash buyer from our network. Either way you get one written offer, one escrow and no fees or commissions.
Do you buy condos as well as houses?
Yes, including condos in HOAs that might be difficult for a traditional buyer to get financed.
How do you calculate your offer?
We use recent comparable Harbor City sales along with your property’s condition and size.
Will the price change after you inspect the house?
No. Because we buy as-is, the offer we make is the offer we close at.
Harbor City is part of the City of Los Angeles. For the citywide picture, see our guide to cash home buyers in Los Angeles.
Seller Guides
Helpful guides for homeowners in Harbor City
Plain-English answers to the questions sellers ask us most.
 Rentals & tenants
Emeryville’s Just Cause Eviction Ordinance: Relocation Pay Under Municipal Code 5-40
Emeryville's Municipal Code 5-40 requires just cause from day one and relocation pay scaled by landlord size, stricter than statewide AB 1482.
Read the guide → Selling for cash
Malibu’s Six-Year Rebuild Deadline After the Palisades Fire: Municipal Code 17.60.020(C)
Malibu gives fire-rebuild applicants six years to file and eight to permit under Code 17.60.020(C), with capped extensions and FEMA rules.
Read the guide → Selling for cash
California’s Security Deposit Cap: How AB 12 Limits What Landlords Can Collect
AB 12 caps most California security deposits at one month of rent, with a narrow two-month exception for small landlords and new 2025 photo rules.
Read the guide → Selling as-is
California Civil Code §4525: The 11 HOA Documents You Must Hand a Buyer Before Closing
California Civil Code 4525 requires HOA sellers to hand buyers 11 documents before closing, including the new balcony inspection report requirement.
Read the guide →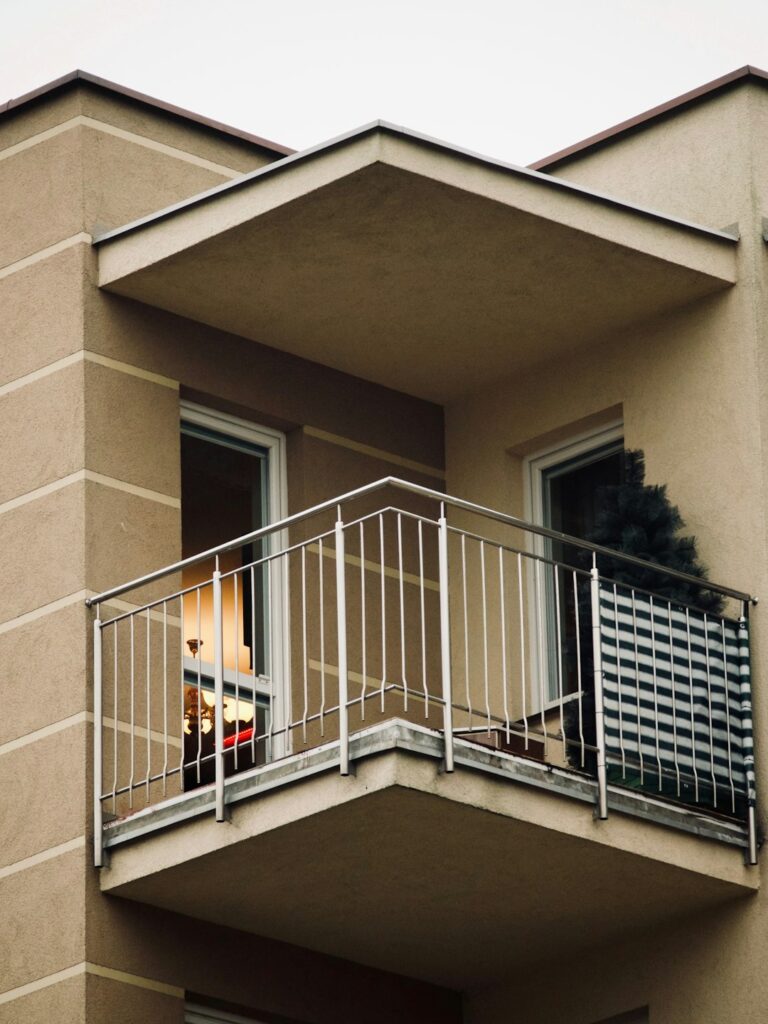 Selling for cash
California’s Balcony Inspection Law: What SB 721 and SB 326 Require Before You Sell
SB 721 and SB 326 require California balcony and deck inspections on rentals and condos, with deadlines already passed. What sellers should check.
Read the guide → Selling for cash
California’s AB 1482 Rent Cap: How the 5% Plus CPI Formula Actually Works
AB 1482's rent cap runs on a 5% plus regional CPI formula, capped at 10%, that resets every August 1. Here's how…
Read the guide → Selling for cash
How to Research Permit History on a Los Angeles Home With LADBS’s PRISM System
LADBS's PRISM system lets you check a home's LA permit history before listing. Here's how the lookup works, what statuses mean, and why lenders care.
Read the guide → Rentals & tenants
California’s Just Cause Eviction Notice: What Civil Code 1946.2 Requires
Civil Code 1946.2 requires a stated reason to end most tenancies after 12 months, and one month's rent in relocation pay within 15 calendar days.
Read the guide → Selling for cash
Pico Rivera Mobilehome Rent Cap: What the Ordinance Limits
Pico Rivera caps mobilehome space rent increases at 3% or 75% of CPI, whichever is less — and the cap follows the…
Read the guide →