
Cash Home Buyers in Valley Village, CA
- Foreclosure, inherited, tenants, damage — we buy it
- Zero fees, zero commissions, zero closing costs
- No obligation — turn the offer down and owe us nothing


Know Who You’re Selling To
See what separates a legitimate Valley Village cash buyer from one that will waste your time, and get a written offer within 24 to 48 hours.
Anyone searching “cash home buyers Valley Village” is usually trying to sort two very different kinds of buyer: a company that will make a firm written offer and close on a real date, and one that strings a seller along with a low number and a long list of conditions.
Cash Home Buyers CA buys houses, condos and small apartment buildings throughout Valley Village directly, and it’s worth knowing what separates a legitimate buyer from one that isn’t before you sign anything.
What a Cash Home Buyer Actually Does
A cash home buyer purchases a property outright, using its own funds or a private line of credit instead of a mortgage. That removes the loan contingency, the lender-ordered appraisal, and the underwriting review that slow down a financed sale.
In Valley Village, where the housing stock runs from 1930s Spanish- and ranch-style bungalows built for studio workers to dingbat-era apartment buildings near the freeways, that matters most on the properties a bank is reluctant to lend against — original wiring, deferred maintenance, or a condo association a lender has flagged.
We look at the property once, usually within a day of hearing from you, and send a written offer within 24 to 48 hours. There’s no showing schedule, no open house, and no financing to fall apart three weeks before closing.
Cash Home Buyers CA is based in Woodland Hills, about a twenty-minute drive west on the 101 from Valley Village, and Valley Village is one of the San Fernando Valley neighborhoods we buy in regularly, alongside North Hollywood, Van Nuys and Sherman Oaks.
How to Tell a Legitimate Buyer From One That Isn’t
- Proof of funds. A real cash buyer can show a bank statement or a letter from its lender confirming the funds exist. If a buyer won’t produce one, that’s a reason to keep looking.
- No repeated re-negotiation. Some buyers make an attractive initial offer, then chip away at the price during a long “inspection period” once you’ve stopped marketing the house elsewhere. A firm number should stay firm absent something the buyer genuinely didn’t know about.
- A named title and escrow company. A legitimate transaction closes through a licensed Los Angeles County title and escrow company, not a private arrangement handled outside escrow.
- A local track record. Cash Home Buyers CA is based in Woodland Hills, about twenty minutes west on the 101, and buys regularly across the San Fernando Valley, including Valley Village, North Hollywood and Van Nuys.
Why Valley Village Fits This Kind of Sale
Valley Village is a small neighborhood, just over two square miles, bounded by Burbank Boulevard, the Tujunga Wash, the Ventura Freeway and the Hollywood Freeway.
It split off from North Hollywood in 1991 after a group of homeowners organized the effort at Colfax Avenue Elementary School, and much of its single-family housing stock still dates to the 1930s.
Movoto’s August 2026 figures put the median list price at $1,095,000, or about $611 per square foot, with 69 homes on the market and a median of 54 days to find a buyer.
An updated bungalow near Colfax Charter Elementary will usually draw a financed buyer without trouble. Original-condition houses, the neighborhood’s older dingbat apartment buildings, and condos in associations a lender hesitates to approve are where a direct cash sale tends to make more sense — and where a scammer is also more likely to target a seller who feels they have no other option.
What the Offer Is Actually Based On
We build a Valley Village offer from recent comparable sales of similar homes and buildings in the immediate area, adjusted for the property’s condition, lot, and (for multi-family buildings) the current rent roll.
We factor in what a retail buyer would have to spend on repairs, the roughly 5 to 6 percent agent commission a listing carries, the combined Los Angeles city and county transfer tax of $5.60 per $1,000 of sale price, and the carrying costs — insurance, utilities, upkeep — a seller avoids by not waiting months for a financed deal to close.
That net comparison, not a lowball starting number meant to be negotiated up, is what we send you.
If you’re also weighing a traditional listing, it’s worth comparing that net number against what a realtor projects after their own commission and closing costs, rather than against the higher list price alone — the list price and the amount that actually lands in your account after a financed sale are two different figures.
How the Escrow and Closing Actually Works
Once you accept a written offer, we open escrow with a licensed Los Angeles County title and escrow company and order a preliminary title report the same day.
Because there’s no lender in the transaction, we also request the Department of Building and Safety’s Report of Residential Property Records — the “9A report” every Los Angeles seller must provide before close — right away, since it usually paces the timeline more than anything else.
The report confirms the seismic gas shutoff valve, water-conserving fixtures, and smoke and carbon monoxide detectors are in place.
For a Valley Village apartment building, we also pull rent rolls and check the property’s Rent Stabilization Ordinance registration status with the city’s Housing Department during escrow, since most of the neighborhood’s pre-1978 buildings fall under RSO.
None of that requires you to clear tenants out or bring the building up to a lender’s standard first. Deeds record at the Los Angeles County Registrar-Recorder/County Clerk’s office in Norwalk, and proceeds wire out the day recording is confirmed.
A clear-title house or condo typically closes in two to three weeks; an occupied apartment building or a probate estate usually takes three to six weeks, on whatever date works for you.
Other Warning Signs to Watch For
- Pressure to sign the same day. A legitimate buyer will give you time to read the purchase agreement and ask questions before signing.
- A request for money up front. You should never be asked to pay a fee to receive an offer or to have your property “evaluated.”
- No local address or verifiable business history. A buyer that’s bought and closed other Los Angeles-area properties before is easier to check up on than one that appeared through a text message with no footprint.
- Assignment of the contract to an unknown third party. Some “we buy houses” operations aren’t buyers at all — they sign a contract intending to resell it to whoever actually has the funds, which adds an extra layer and an extra chance for the deal to fall apart.
Situations Where This Fits Best
A direct sale tends to make the most sense for owners dealing with a Valley Village house inherited from a relative, a rental with tenants already in place, or a property that needs to move on a set date because of a divorce or a relocation.
The same underwriting and appraisal friction that slows a financed sale anywhere else in the city applies here too — see our page on cash home buyers across the rest of Los Angeles if you’re comparing a Valley Village sale to a property elsewhere.
Frequently Asked Questions
Is a cash offer always lower than a listing price?
Usually somewhat lower than what a fully-repaired home might fetch after a long, well-marketed listing. In exchange, there’s no commission, no repair bills, and no risk of a financed deal collapsing.
Do you buy apartment buildings, or only single houses?
Both. We buy houses, condos, and small apartment buildings throughout Valley Village, including buildings with tenants and registered rents in place.
How do I know your offer is real and not a lowball tactic?
We can provide proof of funds, and we close through a licensed Los Angeles County title and escrow company — the same kind of closing a retail buyer would use.
What if my house needs major repairs?
That’s exactly the kind of property a cash sale fits. We buy in current condition, including houses with original wiring, older plumbing, or unpermitted additions common in Valley Village’s 1930s bungalows.
Will you negotiate the price down after we agree?
No, not absent something material we genuinely didn’t know about the property. Our written offer is the number we intend to close at.
Do I have to accept the offer once you send it?
No. You can turn it down and owe us nothing. There’s no obligation to move forward, and no fee for having looked at the property.
What if my Valley Village property has an HOA that’s flagged repairs?
We can still buy it. Special assessments and deferred maintenance are two of the more common reasons a lender declines to approve a condo purchase, and it’s exactly where a direct cash sale is useful.
If you own a house, condo or building in Valley Village, call or text 424-435-2326 for a written cash offer within 24 to 48 hours, with no obligation.
Seller Guides
Helpful guides for homeowners in Valley Village
Plain-English answers to the questions sellers ask us most.
 Relocating
Fontana’s Warehouse Boom: What It Means If You’re Relocating
Fontana grew from a wartime steel town into an Inland Empire logistics hub. See what that shift means for home values and selling if you are relocating.
Read the guide →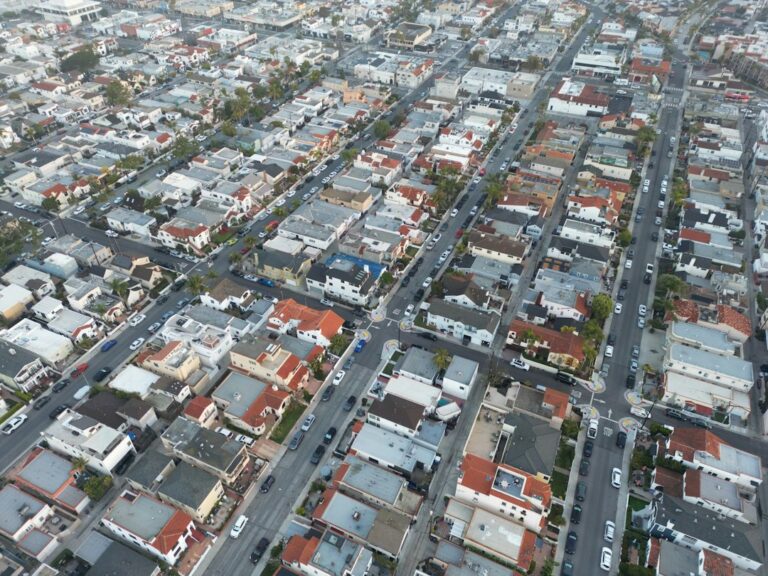 Selling for cash
The Transfer Tax Every Los Angeles Seller Pays, With or Without Measure ULA
Los Angeles charges its own $4.50-per-$1,000 tax on top of the county rate, before Measure ULA applies. See the exact combined math at closing.
Read the guide → Rentals & tenants
How Much Must Long Beach Landlords Pay Tenants Under the Relocation Ordinance?
Long Beach landlords: see the LBMC 8.99 relocation payments, notice periods, and city filing step required before a no-fault tenant termination.
Read the guide → Selling for cash
What Inglewood’s Housing Protection Ordinance Requires Before You Sell a Rental
Inglewood's Housing Protection Ordinance covers more rentals than expected, with rent caps, just-cause rules, and relocation tiers that transfer at sale.
Read the guide → Selling for cash
The Five-Year Countdown Before Los Angeles County Auctions a Tax-Defaulted Home
LA County auctions tax-defaulted homes after five years unpaid. See the redemption deadline, installment options, and how to claim excess proceeds.
Read the guide → Selling for cash
What Beverly Hills’ Rent Stabilization Ordinance Requires Before You Sell
Beverly Hills runs its own BHMC Chapter 5 and 6 rent rules: caps, BHRent registration, just-cause grounds and relocation fees sellers must clear first.
Read the guide → Selling as-is
What Rancho Palos Verdes’ Landslide Zones Mean for a Natural Hazard Disclosure
Rancho Palos Verdes sellers must check a landslide-zone box on the state Natural Hazard Disclosure Statement, separate from the earthquake fault question.
Read the guide → Selling for cash
West Hollywood’s Rent Stabilization Ordinance: What a Seller With Tenants Must Clear First
West Hollywood's rent stabilization law sets strict just-cause rules and relocation fees before you can sell a tenant-occupied rental unit here.
Read the guide → Inherited homes & probate
Partition Actions Between Heirs: How California Law Forces a House Sale
California heirs can force a house sale through a partition action under CCP 872-874, with court referees, confirmation hearings, and buyout rights.
Read the guide →