Sell My House Fast in Miracle Mile
- Foreclosure, inherited, tenants, damage — we buy it
- Zero fees, zero commissions, zero closing costs
- No obligation — turn the offer down and owe us nothing


Skip the HPOZ Repair Clock and the 45-Day Escrow
See how a financed Miracle Mile sale actually plays out against a 7-14 day cash close, and why the gap matters most when you have your own deadline.
If you need to sell a house fast in Miracle Mile, the obstacle is rarely your asking price. It is the sequence of steps a financed buyer has to clear before a sale actually funds, and in a neighborhood where more than 1,300 properties sit inside a Historic Preservation Overlay Zone, that sequence has an extra layer most Los Angeles sellers never deal with. Cash Home Buyers CA buys houses, condos and small apartment buildings throughout Miracle Mile directly, which removes almost all of it.
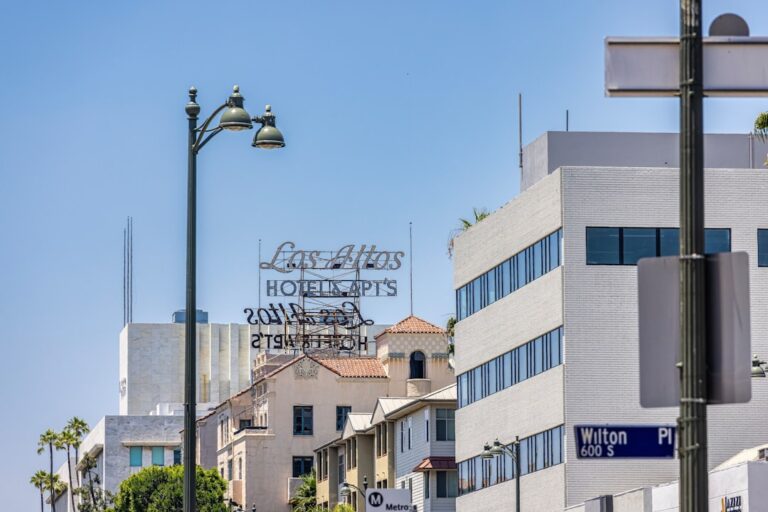
Miracle Mile runs roughly from 3rd Street south to San Vicente Boulevard, and from Fairfax Avenue east to La Brea and Highland, bordering the Fairfax District, Park La Brea, the Grove and Mid-Wilshire. Wilshire Boulevard through the middle of it is Museum Row, anchored by LACMA, the Petersen Automotive Museum, the Academy Museum of Motion Pictures and the La Brea Tar Pits, and it is that mix of walkable culture, ZIP codes 90036 and 90019, and a deep stock of 1920s and 1930s period houses that keeps buyer demand steady even when the broader county market slows down. That demand is exactly why the gap between “under contract” and “funded” matters so much here: interest is rarely the bottleneck, financing is.
How Long a Traditional Miracle Mile Sale Actually Takes
Movoto listed 19 active homes for sale in Miracle Mile as of September 2026, ranging from about $740,000 for a condo up to $3,250,000 for a larger house inside one of the neighborhood’s two HPOZs. A fully restored 1930s Spanish Colonial Revival house near Museum Row can draw an accepted offer within days of hitting the market, especially with buyers competing for a specific block. That fast-offer number is the one sellers usually hear repeated back to them, and it is not the same thing as a closed, funded sale. Once an offer is accepted, a standard California purchase agreement gives the buyer roughly a 17-day contingency period for inspections, disclosure review and loan approval, and full underwriting typically needs another two to four weeks after that. Add it up and a “fast” financed sale in Miracle Mile commonly runs 45 to 60 days from accepted offer to funded escrow, longer if the appraisal or the city’s Report of Residential Property Records turns up something the buyer’s lender wants resolved first.
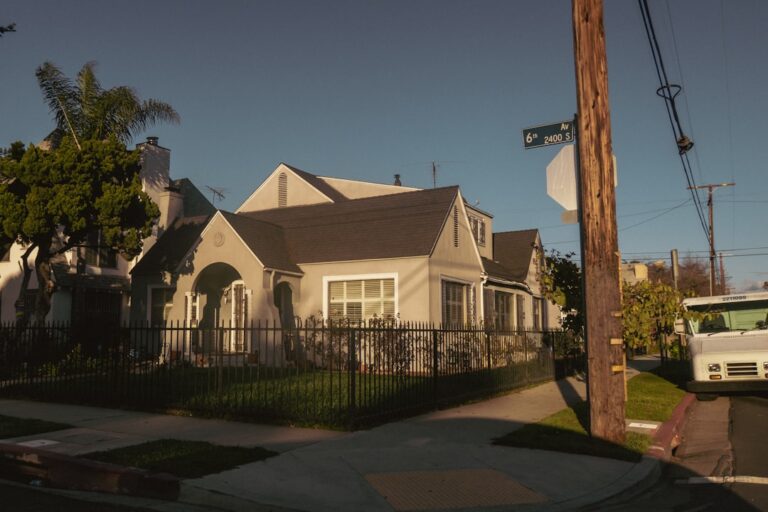
The condos and smaller multi-family buildings south of Olympic Boulevard tend to move on a more conventional timeline than the single-family HPOZ houses to the north, largely because HOA paperwork and estoppel letters, not exterior review boards, are the friction point. North of Olympic, where the housing stock is almost entirely one-story single-family homes built between 1924 and 1941, buyers are often paying a premium specifically for period detail, which raises the stakes if an appraiser or inspector flags something that conflicts with what the listing photos promised.
Where an HPOZ Neighborhood Adds Its Own Delay
Every financed sale carries the same underwriting and appraisal risk. Miracle Mile adds a layer specific to the Miracle Mile HPOZ and the Miracle Mile North HPOZ, which together protect roughly 1,300-plus houses and apartment buildings built mostly between the 1920s and the 1940s. Any exterior work on a contributing property — a re-roof, replacement windows, restuccoing, a second story — needs a Certificate of Appropriateness from the city’s HPOZ Board before it can be done, and that board meets only twice a month, on the first and third Wednesday, at the Fairfax Branch Library. A seller who wants to fix up a house before listing it can lose months waiting on a hearing date alone. The Miracle Mile HPOZ itself covers roughly 1,347 contributing properties between Wilshire Boulevard and San Vicente Boulevard, La Brea Avenue and Orange Grove Avenue, built mostly in Spanish Colonial Revival, Tudor, Mediterranean, French and American Colonial Revival styles, with later Minimal Traditional and mid-century apartment buildings mixed in closer to Olympic. The Miracle Mile North HPOZ, bounded by Gardner and Detroit streets between Beverly Boulevard and 3rd Street, is almost entirely single-family homes from that same 1924-1941 window. None of that history is a problem for a seller who simply wants out; it only becomes a problem the moment a financed buyer’s lender wants exterior work done before it will fund.
- Loan underwriting. A buyer’s pre-approval happens before the offer; full underwriting happens after, and conditions like updated pay stubs or a letter of explanation can add weeks.
- Appraisal mismatch. A restored HPOZ house on a residential block appraises very differently than a mid-century condo near Fairfax and Wilshire, and an appraiser working from the wrong comps can come in under contract price.
- Inspection findings on 1920s-1940s construction. Original wiring, cast-iron plumbing, or an unpermitted rear addition almost always surfaces on inspection, and a buyer’s lender may require it resolved, sometimes with HPOZ-approved materials, before funding.
- Financing falling through late. When a buyer’s loan is denied days before closing, the seller is back to relisting, rescheduling showings and restarting the clock.
What a Cash Sale’s Timeline Looks Like Instead
We typically respond with a written offer within 24 to 48 hours of hearing about your property. Because there is no lender involved, there is no loan contingency and no lender-ordered appraisal to wait on, and no Certificate of Appropriateness needed before we make an offer, since we buy the house exactly as it stands, HPOZ-flagged repairs and all. We still order the city’s Report of Residential Property Records ourselves, but it does not hold up financing the way it does on a conventional sale. Once you accept, we open escrow with a licensed Los Angeles County title and escrow company and can typically close in 7 to 14 days, or on a later date if that fits your move better.
What Happens Between Acceptance and Closing
After you accept our offer, we order a preliminary title report and pull the property’s permit and HPOZ history so nothing surprises anyone at recording. We coordinate the Report of Residential Property Records and the associated retrofit certifications, seismic gas shutoff valve, low-flow fixtures, and smoke and carbon monoxide detectors, ourselves. Los Angeles City and County combined transfer tax runs $5.60 per $1,000 of sale price, normally paid by the seller; on a $1.2 million Miracle Mile house that is roughly $6,700, and we walk you through exactly what comes out of your proceeds before you sign anything. Documents are signed with a mobile notary at a time and place that works for you, and recording happens at the Los Angeles County Registrar-Recorder/County Clerk in Norwalk, with proceeds wired the same day recording is confirmed.
Common Reasons Miracle Mile Homeowners Need to Move Quickly
Speed matters for plenty of ordinary reasons that have nothing to do with a crisis: a new job pulling you toward the Westside or the entertainment industry offices along Wilshire, wanting to avoid carrying two mortgage payments while a new purchase closes, a firm move-out date tied to a lease already signed elsewhere, or not wanting to keep paying insurance and upkeep on a rental sitting empty near Museum Row. Some sellers are simply tired of managing a property from out of state after inheriting it, and others have a tenant situation they would rather hand off than manage through a long marketing period. If your timeline pressure is tied to something more specific, we have dedicated guides that go deeper: foreclosure, divorce, and inherited property in Miracle Mile each come with their own deadlines. The same underwriting, appraisal and escrow rules described here apply to the rest of Los Angeles too — see our page on the rules across the rest of Los Angeles if you are comparing a Miracle Mile sale to a property somewhere else in the city.
The Honest Trade-Off
A cash offer is typically below what a fully restored HPOZ house might fetch after a long, well-marketed retail listing near Museum Row. In exchange, there is no 5 to 6 percent agent commission, no HPOZ hearing to schedule, no repair bills, no months of mortgage and utility payments while you wait, and no risk of the deal collapsing three weeks before closing. Sellers of the roughly $740,000 condos near Fairfax and the larger $2 million-plus HPOZ houses face the same trade-off in different proportions: the condo owner is usually weighing a faster but smaller net against a slower listing with HOA disclosures to gather, while the house owner is weighing months of showings and repair negotiation against a certain number today. For a seller on a real deadline in Miracle Mile, that certainty is usually worth more than the spread.
Frequently Asked Questions
How fast can you really close in Miracle Mile?
Most closings run 7 to 14 days from an accepted offer, though we can move faster or slower depending on what you need.
Do I need HPOZ approval or repairs done before I sell to you?
No. We buy the property exactly as it stands, whether it is a restored Spanish Colonial house or one that still needs HPOZ-approved exterior work. The Certificate of Appropriateness process becomes the new owner’s concern, not yours.
What if I actually need more time, not less?
That is fine. We can set a closing date further out, or arrange a short rent-back so you can stay after closing while you finish your move.
Is a cash sale always faster than listing?
Not always. A move-in-ready HPOZ house near the Grove or Wilshire can attract an offer quickly. The time savings come from skipping the 30 to 45 day financed escrow that follows, plus removing the risk of that escrow falling apart.
Does the new Metro D Line service change how fast my house will sell?
Service to the extended D Line stations at Wilshire/La Brea and Wilshire/Fairfax began in May 2026, and better transit access can help buyer interest, but it does not remove the underwriting and appraisal timeline a financed buyer still has to clear.
Timelines above reflect typical patterns for Los Angeles County escrows and can vary by lender, title company, and the specific property.
Get a free, no-obligation cash offer from Cash Home Buyers CA today.
Selling a house in Miracle Mile: what to know
A few local details that shape timing and net proceeds when you sell in Miracle Mile.
County & probate court
Miracle Mile is a City of Los Angeles neighborhood in Los Angeles County. Probate and trust matters for Miracle Mile properties are heard by the Superior Court for Los Angeles County, and deeds are recorded with the Los Angeles County Recorder.
Transfer tax
Los Angeles County charges a documentary transfer tax of $1.10 per $1,000 of the sale price. The City of Los Angeles adds $4.50 per $1,000, and Measure ULA adds 4% on sales above roughly $5 million (5.5% above roughly $10 million). When you sell to us, we pay the standard closing costs.
Tenant & rent rules
Rental homes in Miracle Mile can fall under the Los Angeles Rent Stabilization Ordinance (RSO), which limits rent increases and requires just cause for most evictions, in addition to the statewide Tenant Protection Act (AB 1482). We buy tenant-occupied homes and take over the leases at closing.
Nearby cities we buy in
Seller Guides
Helpful guides for homeowners in Miracle Mile
Plain-English answers to the questions sellers ask us most.
 Relocating
 From Del Aire, CA: What to Know First
Relocating from Del Aire? This unincorporated LA County community has no city hall, LAX flight-path noise to weigh, and a tax exclusion worth checking.
Read the guide →- Foreclosure & liens
The Foreclosure Timeline for an Artesia, CA Homeowner
Artesia homeowners get about 110 days between a recorded Notice of Default and a trustee sale. Here's how California's two waiting periods work.
Read the guide → - Rentals & tenants
Tenant-Occupied Property Rules in Mayflower Village, CA: Why the County, Not a City, Sets Them
Mayflower Village has an Arcadia address but is unincorporated LA County, so tenant sales follow the county ordinance, not either city's rules.
Read the guide → - Foreclosure & liens
What an Azusa Homeowner Actually Has Before a Trustee Sale
California gives an Azusa homeowner two fixed waiting periods before a trustee sale. Here is exactly how long that is and what the foothill location adds.
Read the guide → - Selling for cash
What Slows Down a Home Sale in San Fernando, CA
San Fernando is its own independent city inside LA, with its own permits and city hall. Here's what that means for a fast, as-is cash sale today.
Read the guide → - Selling for cash
Sell House Fast Los Angeles: The Real Costs of Each Option
Commissions, iBuyer fees, and holding costs compared to a direct cash sale when selling fast in Los Angeles.
Read the guide → - Selling for cash
We Buy Houses in Los Angeles: How the Process Actually Works
Step by step: how a we buy houses sale works in Los Angeles, from first contact to closing in 7-14 days.
Read the guide → - Selling for cash
We Buy Houses Los Angeles: How to Spot a Legitimate Buyer
Red flags, questions to ask, and what a legitimate we buy houses company in Los Angeles actually looks like.
Read the guide → - Selling for cash
Sell My House Fast Los Angeles: Comparing Your 3 Real Options
List, iBuyer, or direct cash sale - real timelines and tradeoffs for selling a house fast in Los Angeles.
Read the guide →