
Sell My House Fast in Old Torrance
- Foreclosure, inherited, tenants, damage — we buy it
- Zero fees, zero commissions, zero closing costs
- No obligation — turn the offer down and owe us nothing


Every Day on the Market Has a Cost
See how a traditional Old Torrance listing timeline compares to a two-to-three week cash close, and why speed matters most when you have a deadline of your own.
If you need to sell a house fast in Old Torrance, the real obstacle usually isn’t your asking price — it’s the chain of steps a financed buyer has to clear before the sale actually funds. Cash Home Buyers CA buys Craftsman bungalows on Gramercy and Andreo, small apartment buildings, and everything in between throughout the historic Old Torrance townsite, and we remove most of that chain entirely.
How Long a Traditional Old Torrance Sale Actually Takes
Redfin’s figures for the 90501 zip code, which covers Old Torrance and the surrounding downtown blocks, put the three-month median sale price at $999,774 as of June 2026, up 16.3 percent from a year earlier, on 55 homes sold with a median of 44 days on market.
That number is how long it takes to go into contract, not how long it takes to close.
Once an offer is accepted, a standard California residential purchase agreement gives the buyer roughly a 17-day contingency period to complete inspections, review disclosures, and finalize loan approval, and the loan itself typically needs another two to four weeks after that for underwriting and final sign-off.
Add it up and a “fast” traditional sale in Old Torrance is commonly 45 to 60 days from accepted offer to funded escrow, longer if anything about the house or the title needs sorting out.
Where a Financed Sale Actually Loses Time
- Loan underwriting. A buyer’s pre-approval happens before the offer; full underwriting happens after, and conditions like updated pay stubs or letters of explanation can add weeks.
- A low appraisal. A restored 1910s or 1920s Craftsman bungalow on Gramercy or Andreo, with original details and a detached garage off the alley, appraises very differently than a similar-looking house a few blocks over that’s been a rental for decades, or a unit in one of the small 1930s-through-1950s apartment buildings that fill in the surrounding blocks. An appraiser working from the wrong comps can come in under the contract price and force a renegotiation.
- Inspection renegotiation. A general inspection on an original Old Torrance bungalow with knob-and-tube wiring, an old sewer lateral, or an unpermitted garage conversion almost always turns something up, and the repair-credit negotiation that follows can add one to two weeks even when both sides want the deal to close.
- Financing falling through late. When a buyer’s loan is denied days before closing, the seller is back to square one: relisting, rescheduling showings, and restarting the whole clock.
What a Cash Sale’s Timeline Looks Like
We typically respond with a written offer within 24 to 48 hours of hearing about your property. Because there is no lender involved, there is no loan contingency and no lender-ordered appraisal to wait on.
Torrance is its own incorporated city, not part of Los Angeles, so there is also no Los Angeles Department of Building and Safety 9A report to hold things up the way it can on a Los Angeles city sale — you’ll still sign a standard transfer disclosure statement and any required smoke and CO detector certifications, but that’s a much shorter list.
Once you accept, we open escrow with a licensed South Bay title and escrow company and, on a house with clear title, can typically close in two to three weeks.
Estates and tenant-occupied buildings usually run three to five weeks, mostly to allow time to document the tenancy or clear a probate step. Either way, you choose the date.
Common Reasons Old Torrance Homeowners Need to Move Quickly
Speed matters for plenty of ordinary reasons that have nothing to do with a crisis: a new job with one of the South Bay’s aerospace or logistics employers pulling you elsewhere, wanting to avoid carrying two mortgage payments while a new purchase closes, a firm move-out date tied to a lease already signed elsewhere, or simply not wanting to keep paying insurance and upkeep on a bungalow sitting empty near the old Pacific Electric depot.
If your timeline pressure is tied to something more specific, we have dedicated guides that go deeper: foreclosure, divorce, and relocation in Old Torrance each come with their own deadlines.
The same underwriting, appraisal, and escrow rules described here apply across the rest of Los Angeles too, if you’re comparing a South Bay sale to a property elsewhere in the county.
The Honest Trade-Off
A cash offer is typically below what a fully-restored bungalow might fetch after a long, well-marketed retail listing that leans on the block’s historic character.
In exchange, there’s no 5 to 6 percent agent commission, no repair bills for old wiring or a cracked sewer line, no months of mortgage and utility payments while you wait, and no risk of the deal collapsing three weeks before closing.
For a seller on a real deadline in Old Torrance, that certainty is usually worth more than the spread.
The Paperwork and Fees a Cash Sale Lets You Skip
A financed Old Torrance sale still carries its own short list of required reports and closing costs even after a buyer is found.
California law requires the seller to provide a Natural Hazard Disclosure (NHD) report, prepared by a licensed third-party provider rather than the seller or their agent, showing whether the property sits in a flood, wildland fire, seismic hazard, or earthquake fault zone; it typically costs $70 to $100 and is usually delivered around the time of the buyer’s home inspection, after which the buyer has a few days to review it.
Escrow fees are customarily split evenly between buyer and seller, and in Southern California it’s customary for the seller to pay for the buyer’s owner’s title insurance policy.
None of those costs go away with any buyer, cash or financed, but selling directly to us skips the inspection-driven renegotiation and repair-credit disputes that usually follow once that paperwork surfaces an issue.
What Happens During the Standard 17-Day Contingency Period
On a financed sale, the standard California residential purchase agreement gives the buyer a roughly 17-day window to remove three separate contingencies: investigation (physical and pest inspections, review of permit history and any homeowners’ association documents), loan approval, and appraisal.
Each one runs on its own clock, and any one of them can extend if the buyer asks and the seller agrees.
A buyer can cancel and walk away with their deposit during this window for almost any reason tied to what the inspection or appraisal turns up, which is exactly the leverage that leads to repair-credit negotiations on an original Old Torrance bungalow.
A cash sale has no loan or appraisal contingency to run out the clock, and we don’t require a formal inspection period before making our offer.
Every Extra Week on the Market Has a Real Carrying Cost
Property tax under California’s Proposition 13 framework generally runs around 1 percent of assessed value plus voter-approved local assessments, commonly landing near 1.1 to 1.25 percent altogether, and that accrues every month a house sits unsold regardless of who eventually buys it.
Add a hazard insurance policy and, if the property sits vacant during a transition, ongoing utilities and basic upkeep, and the math behind a 45-to-60-day financed escrow gets more expensive the longer it runs.
None of that is optional while a sale drags on, and it keeps accruing during any post-inspection renegotiation delay too.
Frequently Asked Questions
How fast can you really close on an Old Torrance house?
Typically two to three weeks for a house with clear title, since there’s no city 9A report to wait on here. Estates or tenant-occupied buildings usually take three to five weeks.
Does the historic district review slow down a fast sale?
No. Old Torrance is under review for historic district status but isn’t yet designated, so it doesn’t add any approval step to selling the property itself.
Do I need to fix the old wiring or a garage conversion first?
No. We buy the property in its current condition, including original knob-and-tube wiring or an unpermitted addition.
What if I actually need more time, not less?
That’s fine. We can set a closing date further out, or arrange a short rent-back so you can stay after closing while you finish your move.
Is a cash sale always faster than listing?
Not always — a well-priced, restored bungalow on Gramercy or Andreo can attract an offer quickly. The time savings come from skipping the 30 to 45 day financed escrow that follows, plus removing the risk of that escrow falling apart.
Timelines above reflect typical patterns for South Bay escrows and can vary by lender, title company, and the specific property.
Why the 90501 Comps Move the Way They Do
A single zip code median hides a lot of variation between a restored Craftsman on Gramercy or Andreo and a mid-century house a few blocks toward the 405, or a unit inside one of the small 1930s-through-1950s apartment buildings scattered through the area.
That spread is exactly why we look at the specific block and property type rather than quoting a single number off a zip-code-wide report, and it's also why two houses that look similar on paper can support very different offers once condition, permitting history, and occupancy are factored in.
Get a free, no-obligation cash offer from Cash Home Buyers CA today.
Seller Guides
Helpful guides for homeowners in Old Torrance
Plain-English answers to the questions sellers ask us most.
 Relocating
Fontana’s Warehouse Boom: What It Means If You’re Relocating
Fontana grew from a wartime steel town into an Inland Empire logistics hub. See what that shift means for home values and selling if you are relocating.
Read the guide →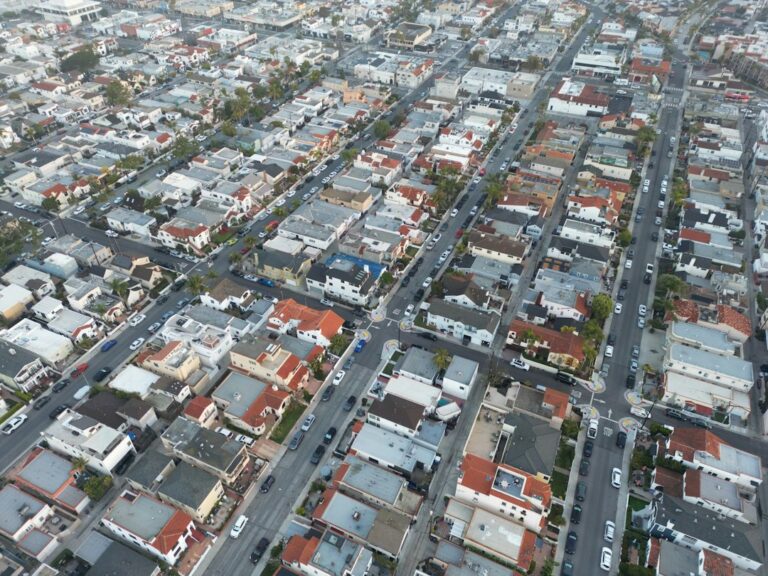 Selling for cash
The Transfer Tax Every Los Angeles Seller Pays, With or Without Measure ULA
Los Angeles charges its own $4.50-per-$1,000 tax on top of the county rate, before Measure ULA applies. See the exact combined math at closing.
Read the guide → Rentals & tenants
How Much Must Long Beach Landlords Pay Tenants Under the Relocation Ordinance?
Long Beach landlords: see the LBMC 8.99 relocation payments, notice periods, and city filing step required before a no-fault tenant termination.
Read the guide → Selling for cash
What Inglewood’s Housing Protection Ordinance Requires Before You Sell a Rental
Inglewood's Housing Protection Ordinance covers more rentals than expected, with rent caps, just-cause rules, and relocation tiers that transfer at sale.
Read the guide → Selling for cash
The Five-Year Countdown Before Los Angeles County Auctions a Tax-Defaulted Home
LA County auctions tax-defaulted homes after five years unpaid. See the redemption deadline, installment options, and how to claim excess proceeds.
Read the guide → Selling for cash
What Beverly Hills’ Rent Stabilization Ordinance Requires Before You Sell
Beverly Hills runs its own BHMC Chapter 5 and 6 rent rules: caps, BHRent registration, just-cause grounds and relocation fees sellers must clear first.
Read the guide → Selling as-is
What Rancho Palos Verdes’ Landslide Zones Mean for a Natural Hazard Disclosure
Rancho Palos Verdes sellers must check a landslide-zone box on the state Natural Hazard Disclosure Statement, separate from the earthquake fault question.
Read the guide → Selling for cash
West Hollywood’s Rent Stabilization Ordinance: What a Seller With Tenants Must Clear First
West Hollywood's rent stabilization law sets strict just-cause rules and relocation fees before you can sell a tenant-occupied rental unit here.
Read the guide → Inherited homes & probate
Partition Actions Between Heirs: How California Law Forces a House Sale
California heirs can force a house sale through a partition action under CCP 872-874, with court referees, confirmation hearings, and buyout rights.
Read the guide →